Annuities
Annuities for guaranteed growth and retirement income
Fixed, fixed indexed and income annuities from top-rated carriers, with product comparisons, illustrations and case design from the SRS team.
In short: an annuity is a contract with an insurance company that grows money tax-deferred and can turn savings into guaranteed income. Fixed annuities credit a declared rate, fixed indexed annuities credit interest linked to a market index without losing value when the index falls, and income annuities pay a guaranteed stream that can last for life. The right fit depends on the client’s time horizon, need for access to the money and income goals.
What we place
Annuity solutions for every retirement stage
Fixed-rate and multi-year guaranteed annuities
A declared interest rate guaranteed for a set term, often 3 to 10 years. Many contracts allow limited free withdrawals each year.
Fixed indexed annuities
Interest linked to an index such as the S&P 500, subject to caps or participation rates, with no loss of value when the index goes down.
Lifetime income riders
Optional riders on many deferred annuities that guarantee withdrawals for life, even if the account value runs out.
Immediate and deferred income annuities
Turn a lump sum into guaranteed income that starts now or at a chosen future date, including income for two lives.
Annuities with long-term care benefits
Annuity-based LTC coverage for clients who are older or have health issues. See how it works.
Qualified money, rollovers and 1035 exchanges
Help positioning IRA and 401(k) rollovers, required minimum distributions and exchanges from older contracts.
How we help
Support from quote to delivery
Product and case design
- Annuity Hotpicks: current fixed, indexed and income annuity highlights, emailed to advisors every week
- Side-by-side comparisons across carriers
- Illustrations for fixed, indexed and income products
- Income planning and rider analysis
- Legacy strategies, including repositioning unneeded annuities into life insurance
Getting the business placed
- Contracting and appointments
- Help with carrier product training and state annuity training requirements
- Suitability and best-interest paperwork review
- Case tracking in the My Business Portal
Annuity and retirement guides
Articles for advisors
- Tax-deferred vs. taxable: how to explain an annuity’s real yield
- Annuity maximization: repositioning deferred annuities to fund life insurance
- Hybrid long-term care annuities for clients over 70
- Using RMDs to fund life insurance
- Using RMDs to fund survivorship life insurance
- Using life insurance to supplement retirement income
Who you’ll work with
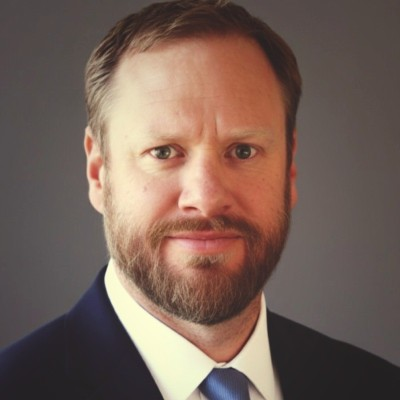
Tim Fuller
President, SRS Inc. · Littleton, Colorado
SRS has helped advisors place life, disability, long-term care and annuity cases for more than 50 years, with a focus on impaired risk underwriting and advanced planning. When you send a case, you work directly with our team, not a call center.
Get help
Two ways to start
Advisors get quotes, comparisons and case design. Individuals can talk directly with Tim Fuller.
For advisors
Request an annuity quote
Tell us the client’s age, premium, money type and goal. We will compare carriers and send illustrations. Submit online or download the request form.
For individuals and families
Talk to Tim
Planning your own retirement income? Tim will walk you through the options. No cost, no pressure.
Or call 303-309-3471
FAQ
Annuity questions
What is the difference between a fixed annuity and a fixed indexed annuity?
A fixed annuity credits a rate the insurance company declares, often guaranteed for a set number of years. A fixed indexed annuity credits interest based on the performance of a market index, subject to caps or participation rates, and does not lose value when the index goes down.
Can a client lose money in a fixed indexed annuity?
Not from index declines. Value can be reduced by surrender charges on withdrawals above the free amount during the surrender period, and by optional rider fees.
How are annuity earnings taxed?
Growth is tax-deferred until it is withdrawn. Gains come out as ordinary income, and withdrawals before age 59½ may also face a 10% federal penalty. Clients should confirm their situation with a tax professional.
What is a 1035 exchange?
Section 1035 of the tax code lets a client move an existing annuity or life insurance contract into a new annuity without paying tax on the gain at the time of the exchange. Surrender charges on the old contract and the features being given up should be reviewed first.
Can individuals work with SRS directly?
Yes. If you are planning for your own retirement, you can talk directly with Tim Fuller about your options. There is no cost and no pressure.
Guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Annuities are long-term contracts; surrender charges may apply to early withdrawals. This page is general information, not tax or legal advice.