Free for financial professionals
Annuity 101 cheat sheet for agents
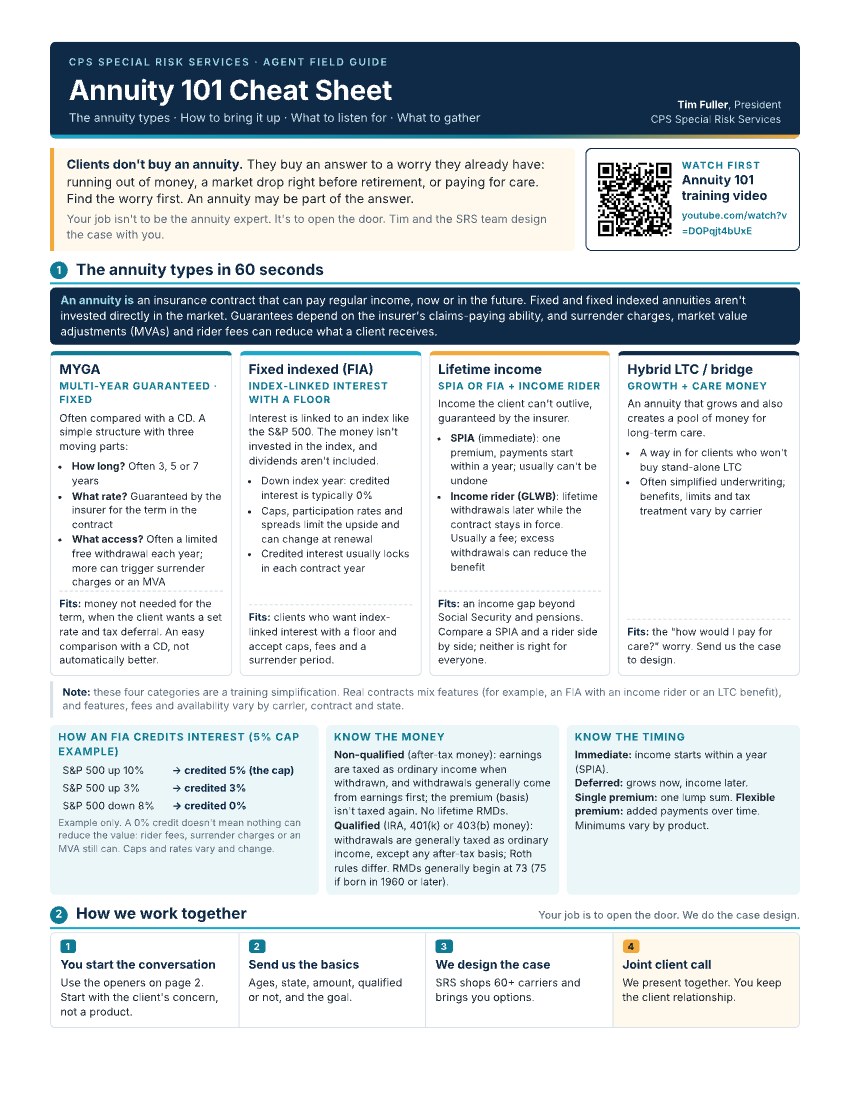
A free three-page field guide for agents who are new to annuities. It explains the main annuity types in plain English, gives you 11 ways to start the conversation, and lists exactly what to gather before you call us.
What’s inside
Built for your first annuity conversations
Clients don’t buy an annuity. They buy an answer to a worry they already have: running out of money, a market drop right before retirement, or paying for care. The cheat sheet helps you find that worry first.
The annuity types in 60 seconds
MYGA, fixed indexed, lifetime income and hybrid LTC, with who each one fits.
How to bring it up
A four-step process and 11 openers built on real retirement concerns.
What to listen for
Ten things clients say that signal an annuity conversation, and the next question to ask.
What to gather
A checklist of client, liquidity, goal and replacement details so we can quote and check suitability in one pass.
Guardrails
Fit, costs, the difference between free withdrawals and the IRS 10% additional tax, best-interest standards and compliant language.
How we work together
You open the door. SRS designs the case and joins the client call.
Annuity basics
The annuity types in 60 seconds
An annuity is an insurance contract that can pay regular income, now or in the future. Fixed and fixed indexed annuities aren’t invested directly in the market, but their guarantees depend on the issuing insurer’s claims-paying ability, and surrender charges, market value adjustments and rider fees can reduce what a client receives. These four categories are a training simplification: real contracts often combine features, and features vary by carrier, contract and state.
MYGA
A multi-year guaranteed annuity: a rate guaranteed by the insurer for a set term, often 3, 5 or 7 years, with tax-deferred growth. Withdrawals above the contract’s free amount can trigger surrender charges or a market value adjustment.
Fits: money not needed for the term. Easy to compare with a CD, but not automatically better.
Fixed indexed (FIA)
Interest is linked to an index such as the S&P 500, limited by a cap, participation rate or spread that can change at renewal. In a down index year credited interest is typically 0%, but rider fees, surrender charges or an adjustment can still reduce the value.
Fits: clients who want index-linked interest with a floor and accept the limits and surrender period.
Lifetime income
A single premium immediate annuity (SPIA) starts payments right away. An income rider (GLWB) on an FIA allows lifetime withdrawals later while the contract stays in force; riders usually carry a fee, and withdrawals above the rider’s limit can reduce the benefit.
Fits: an income gap beyond Social Security and pensions. Compare both; neither is right for everyone.
Hybrid LTC / bridge
An annuity that grows and also creates a pool of money for long-term care, often with simplified underwriting. Benefits, limits and tax treatment vary by carrier.
Fits: the “how would I pay for care?” worry.
Product features, caps and rates vary by carrier and change over time. See all the annuities we place on our annuities page.
Watch
Watch Agent Annuity 101
Prefer to watch first? Our Agent Annuity 101 video walks through the same ideas as the cheat sheet. Watch it, then keep the cheat sheet next to you for your next client review.
Start the conversation
How to bring up annuities with clients
Start with the client’s retirement concerns, never with a product. The cheat sheet gives you this four-step process:
Ask what they want
Where is the money now, and what does retirement income look like?
Listen for idle or at-risk money
CDs, savings, bonds, old 401(k)s and IRAs no one is managing.
Fit it to the client
Recommend only what fits their goals, liquidity and time horizon, and document why.
Bring us in
Tim joins the call to design the case with you.
The CD conversation
“When your CD renews, would you like to compare it with a fixed annuity that guarantees a rate for a set term and defers tax on the interest? Each has trade-offs.”
Getting down the mountain
“You’ve done a great job climbing the mountain. Has anyone talked to you about how to get down it safely, once the withdrawals start?”
Income they can’t outlive
“How much guaranteed lifetime income do you have, money that pays no matter how long you live?”
Eight more openers, the “what to listen for” table and the intake checklist are in the free download.
Get the guide
Download the cheat sheet
For licensed insurance professionals
Send me the Annuity 101 cheat sheet
The download link appears right after you submit the form.
Have a case now?
Let SRS design it with you
When a client is ready, send us the basics: ages, state, amount, whether the money is qualified or not, and the goal. SRS shops 60+ carriers, brings you options and joins the client call. You keep the relationship.
Not contracted with SRS yet? Get contracted or call 303-309-3471.
Who you’ll work with
Tim Fuller
President, SRS Inc. · Littleton, Colorado
SRS has placed life, disability, long-term care and annuity cases for over 50 years. When you send a case, you work directly with our team, not a call center.
FAQ
Annuity cheat sheet questions
What is in the Annuity 101 cheat sheet?
Three pages: the main annuity types in plain English, a four-step process and 11 conversation openers, ten things clients say that signal an annuity need, an intake checklist, compliance guardrails, and how SRS works with you on a case.
Who is the cheat sheet for?
Licensed insurance agents and financial professionals, especially life, P&C and Medicare agents who are new to annuities. It is for agent training only and is not meant to be given to clients.
Where do many agents start with annuities?
Many agents start with a multi-year guaranteed annuity (MYGA). It has three moving parts (how long, what rate, what access), and most clients already understand CDs, so the comparison is easy to explain. Whether it fits depends on the client.
How much of a client’s money should go into an annuity?
There is no standard percentage. Under the NAIC best-interest model regulation, as adopted in each state, a recommendation has to be based on the client’s own financial situation, liquidity needs, time horizon and goals, and the reasons have to be documented.
How does SRS help with annuity cases?
Send us the basics and we shop 60+ carriers, prepare illustrations and comparisons, review suitability paperwork and join the client call. Start with the annuity quote request.
For licensed insurance professionals. Not for client distribution. Annuities are not bank deposits and are not FDIC-insured. Guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Product features, caps and rates vary by carrier, contract and state and change over time. Withdrawals may be subject to surrender charges, market value adjustments and taxes, and the taxable part of a withdrawal before age 59½ may be subject to a 10% IRS additional tax unless an exception applies. Not tax or legal advice; clients should consult a tax professional.