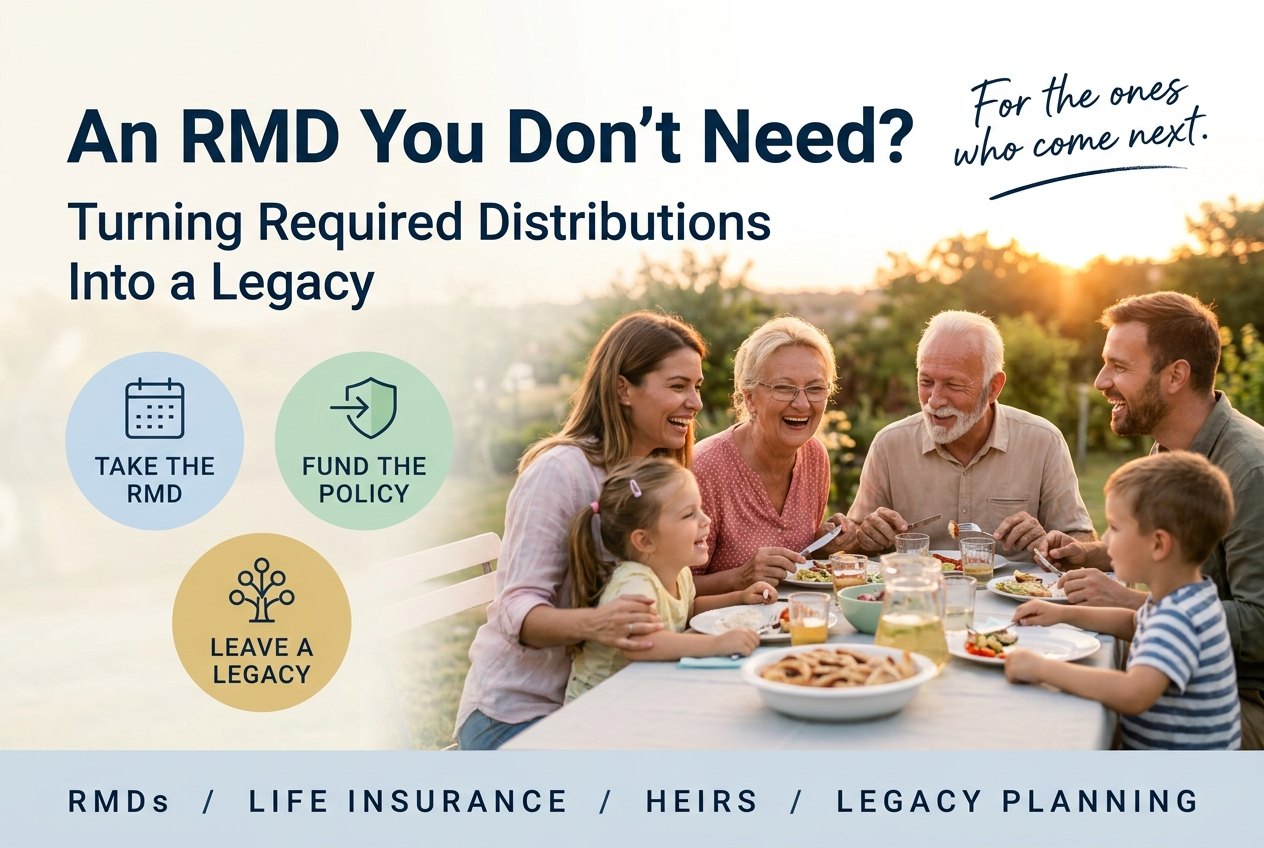
Some retirees take their required minimum distribution, pay the tax, and use what is left to pay premiums on a permanent life insurance policy. Money they always planned to leave to family becomes a larger death benefit that heirs generally receive free of income tax. It is one of several good options for an RMD you do not need, alongside giving to charity directly from your IRA.
Key takeaways
- RMDs start at age 73 for people born 1951 through 1959, and at 75 for people born in 1960 or later.
- Most non-spouse heirs must empty an inherited IRA within 10 years and pay income tax on it.
- Life insurance death benefits generally pass to beneficiaries free of income tax.
- Coverage requires underwriting, and costs rise with age, so compare options before deciding.
Why unneeded RMDs are a problem
Once RMDs begin, you must withdraw a minimum amount from traditional IRAs and most employer plans each year and pay income tax on it, whether you need the money or not. Under SECURE 2.0 the starting age is 73 for people born from 1951 through 1959 and 75 for those born in 1960 or later.
Whatever is left in the IRA at death is not tax-free for your heirs either. Most non-spouse beneficiaries must withdraw an inherited IRA within 10 years, often during their own peak earning years, and pay income tax at their rates.
How the strategy works
- Take the RMD as required and pay the income tax.
- Use some or all of the after-tax amount to pay premiums on a permanent life insurance policy.
- At death, beneficiaries generally receive the death benefit free of income tax.
For pure legacy goals, guaranteed universal life or a survivorship (second-to-die) policy on a married couple is often the most efficient. Indexed universal life or whole life fits people who also want access to cash value if plans change.
If the money is going to your children anyway, the question is how much of it the IRS takes along the way.
Other options to compare
| Option | Best when | Watch for |
|---|---|---|
| Qualified charitable distribution (QCD) | You give to charity anyway | Must go directly from an IRA to a qualified charity; annual limit applies |
| Spend or gift it | You want to help family now | Gifts above the annual exclusion need a gift tax return |
| Invest in a taxable account | You want full access and flexibility | Future growth is taxable; heirs get a step-up in basis |
| Fund life insurance | The money is meant for heirs and you are insurable | Underwriting, cost at older ages, estate inclusion |
Things to check first
- Health and age. Coverage requires underwriting. SRS specializes in placing coverage for people with health conditions, but cost rises with age.
- Estate tax. The death benefit is generally free of income tax but can be included in your taxable estate if you own the policy. Large estates often use an irrevocable life insurance trust (ILIT); talk with an estate attorney.
- Commitment. The premium needs to be paid for the life of the policy unless it is designed with a limited pay period.
Frequently asked questions
Can I use my RMD to pay premiums directly from the IRA?
No. The RMD is distributed to you and taxed first. You then pay the premium with the after-tax money.
Do I have to be healthy to do this?
Coverage requires underwriting, but many health conditions can still be insured. Pricing depends on age and health.
Is the death benefit tax-free?
Life insurance death benefits are generally free of income tax to beneficiaries. They can be subject to estate tax if the policy is in your estate.
Is this better than a qualified charitable distribution?
They serve different goals. A QCD is best if you want to support charity; life insurance is designed to move more to your heirs.
Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.
Sources: IRS: required minimum distribution FAQs
General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.
Reviewed by Tim Fuller on 2026-09-30

Tim Fuller
President, SRS Inc.
Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.
Connect on LinkedIn →We’re Here to Help
Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.