Call 303-309-3471 Advisors: get contracted with SRS →Get a Quote

MYGA vs. CD: How a Multi-Year Guaranteed Annuity Compares to a Bank CD

Woman comparing two documents at her kitchen table with coffee and a laptop

A multi-year guaranteed annuity (MYGA) and a bank CD both lock in a guaranteed rate for a set number of years. The big differences are taxes, access to your money and who stands behind the guarantee. In a taxable account, CD interest is taxed each year as it’s earned, while interest in a non-qualified MYGA is tax-deferred until you take money out. A CD is FDIC-insured up to the limits; a MYGA is backed by the insurance company that issues it.

Key takeaways

  • Both give a guaranteed rate for a set term, most often 3, 5 or 7 years for a MYGA.
  • Outside an IRA, CD interest is taxed each year; non-qualified MYGA interest is tax-deferred until withdrawn. Inside an IRA, both follow the IRA’s rules.
  • Most MYGAs allow a free withdrawal each year; larger withdrawals during the term carry a surrender charge.
  • A CD is FDIC-insured up to the limits; an annuity is not FDIC-insured and is backed by the issuing insurance company.
  • The free-withdrawal allowance only avoids the insurer’s surrender charge. Separately, the taxable part of a withdrawal before 59½ can face a 10% IRS additional tax unless an exception applies.

What is a MYGA?

A MYGA is a fixed annuity that pays a guaranteed interest rate for a set term. It has only three moving parts: how long the money is committed, what rate is guaranteed for that period, and how much you can take out along the way. That simplicity is why it is often called the CD alternative.

MYGA vs. CD side by side

Bank CDMYGA (fixed annuity)
Guaranteed rate for the termYesYes
Taxes on interest (taxable account)Taxed every year as earned (you get a 1099-INT)Tax-deferred until withdrawn (non-qualified MYGA)
CompoundingInterest left in the CD compounds; in a taxable account, tax on it is due each year, whether you pay it from the CD or other moneyInterest compounds, and in a non-qualified MYGA no tax is due on it until it is withdrawn
Access before the term endsEarly withdrawal penaltyOften a limited free withdrawal each year (varies by contract); surrender charge and possibly a market value adjustment above that
Who backs itFDIC, up to its limitsThe issuing insurance company (not FDIC-insured)
Before age 59½No IRS additional tax (bank penalty may apply)10% IRS additional tax on the taxable part, unless an exception applies

Product details vary by carrier, so always check the specific contract.

Taxes: why deferral matters

In a regular taxable account, CD interest is taxed in the year it’s earned, even if you leave it in the CD to compound. You pay that tax from the CD or from other money. In a non-qualified MYGA (one bought with money that has already been taxed), interest also compounds, but no income tax is due on it until you withdraw it. Over a long term, deferring tax can leave more of the interest working for you, but the difference depends on your tax bracket now and when you withdraw.

Inside an IRA or other tax-qualified account, the comparison changes: a CD held in an IRA also grows tax-deferred, and withdrawals from either follow the IRA’s rules. So for IRA money, the main differences are the rate, the term, access and who backs the guarantee, not tax deferral.

When you do withdraw from a non-qualified annuity (one bought with money that has already been taxed), the IRS treats the money as coming from earnings first, and those earnings are taxed as ordinary income; your original premium isn’t taxed again (IRS Publication 575). The taxable part of a withdrawal before age 59½ can also be subject to a 10% additional tax unless an exception applies (IRS Topic 558). For a closer look at the math, see Tax-deferred vs. taxable: how to explain an annuity’s real yield.

Access to your money

A CD usually charges an early withdrawal penalty if you cash it in before it matures. Many MYGAs let you take out part of the value each year without a surrender charge, such as a percentage of the value or the interest earned; the amount varies by contract. Taking more than that during the term triggers a surrender charge that usually declines each year, and some contracts also apply a market value adjustment. A free withdrawal avoids the surrender charge, but not taxes. Keep an emergency fund outside the annuity so you don’t need to touch it early.

Who stands behind the guarantee

Bank deposits are insured by the FDIC. The standard amount is $250,000 per depositor, per insured bank, for each account ownership category (FDIC). A MYGA is not a bank product and is not FDIC-insured (FDIC: financial products that are not insured). Its guarantees rest on the financial strength and claims-paying ability of the insurance company that issues it, which is why we compare carriers’ financial ratings, not just their rates.

Rates on both CDs and MYGAs change often. If you are comparing the two, compare current quotes for the same term on the same day.

Who a MYGA fits, and who it doesn’t

  • A MYGA may fit if you: have money in CDs or savings you won’t need for the term, are near or in retirement, and want a guaranteed rate with tax-deferred growth.
  • A CD may fit better if you: may need the money before the term ends, are under 59½ and may need to withdraw, or want FDIC coverage on that money.

If the money is in an IRA, required minimum distributions still apply once they begin, generally at age 73 (IRS), or 75 for people born in 1960 or later (Treas. Reg. §1.401(a)(9)-2). Talk with a tax professional about your situation.

How SRS can help

We compare MYGA rates and carriers across our 60+ carrier relationships and walk you through the trade-offs in plain English. There’s no cost to talk. Talk to Tim or call 303-309-3471. Want to see the other types? Our annuities page covers fixed, fixed indexed and income annuities.

Financial professionals: the MYGA vs. CD conversation is the first opener in our free Annuity 101 cheat sheet for agents.

Frequently asked questions

Is a MYGA better than a CD?

It depends on your goals. A MYGA offers tax-deferred growth and a guaranteed rate, while a CD offers FDIC insurance up to the limits and no IRS additional tax before 59½. People near retirement with money they won’t need for the term often compare both.

Is a MYGA FDIC insured?

No. A MYGA is backed by the financial strength and claims-paying ability of the insurance company that issues it, not by the FDIC.

Can I take money out of a MYGA early?

Many MYGAs allow a limited free withdrawal each year; the amount varies by contract. Taking more during the term usually triggers a surrender charge and possibly a market value adjustment. Separately, the taxable part of a withdrawal before age 59½ can face a 10% IRS additional tax unless an exception applies.

How long are MYGA terms?

The most popular terms are 3, 5 and 7 years. At the end of the term you can usually renew, move the money to another annuity or take it out.

Sources: IRS Publication 575: pension and annuity income; IRS Topic 558: additional tax on early distributions; IRS: required minimum distributions; Treas. Reg. §1.401(a)(9)-2; FDIC: understanding deposit insurance; FDIC: financial products that are not insured

General information, not tax or legal advice. Annuities are not bank deposits and are not FDIC-insured. Guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Product features, caps and rates vary by carrier, contract and state.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-10-14

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.

Sequence of Returns Risk: How to Explain It to Clients (With a Simple Example)

Retired couple hiking hand in hand down a mountain trail at sunset

Sequence of returns risk is the risk that bad market years come early in retirement, while a client is taking withdrawals. Two retirees can earn the exact same average return and end up with very different results, simply because the losses came in a different order. It matters most in the first years of retirement, which is why it belongs in every retirement income conversation.

Key takeaways

  • Sequence of returns risk is about the order of returns, not the average.
  • It matters most once withdrawals start, especially in the first years of retirement.
  • Losses take bigger gains to recover: a 20% loss needs a 25% gain to break even.
  • Protecting a portion of retirement money from market loss can soften the damage of early bad years.

What is sequence of returns risk?

While a client is saving, the order of returns doesn’t change much. A bad year early on just means buying at lower prices, and there is time to recover. Once withdrawals start, the order matters a lot. Money taken out after a loss is gone for good, and it can’t be there when the market recovers.

We describe it as climbing the mountain versus getting down it. The accumulation years are the climb: save, invest and recover from bad years. Retirement is the way down. Most of the attention in the financial industry goes to the climb, and far fewer people talk with clients about getting down safely.

A simple way to picture it

Picture two retirees who start with the same savings, take the same withdrawals each year and earn the same set of yearly returns over retirement. The only difference is the order: one gets the strong years first and the losses later, and the other gets the losses first and the strong years later.

Their average return is identical, but their results are not. The retiree who takes losses early is selling investments at lower prices to fund withdrawals, so less money is left to benefit when the market recovers. In many scenarios like this, that retiree runs out of money years sooner. This is a concept illustration, not a projection of any product or portfolio.

No one has a crystal ball. A client controls when they retire, but not the returns they get in their first few years of retirement.

Why losses hurt more than gains help

After a loss, a smaller balance has to grow by a bigger percentage just to get back to where it started. The math is simple: the gain needed equals the loss divided by (1 minus the loss).

LossGain needed to break even
10%11.1%
20%25%
30%42.9%
50%100%

Those break-even numbers are before any withdrawals. When a retiree is also taking income out, the climb back is steeper still.

How to explain it to a client

Keep it short and ask a question instead of making a statement:

“No one controls what the market does in their first few years of retirement. Can I show you why the order of returns matters as much as the average?”

Then walk through the two-retiree example, and ask how much of their retirement money would have to be sold after a loss in those first years. You’ll find more openers like this in How to bring up annuities with clients.

Ways to manage sequence of returns risk

There is more than one tool. Common approaches include keeping a cash reserve for the first years of withdrawals, being flexible about how much is withdrawn after a bad year, and protecting part of the portfolio from market loss. An annuity is one way to do the last one:

  • Fixed and multi-year guaranteed annuities (MYGAs) credit a rate declared or guaranteed by the insurer, so their value isn’t tied to market performance. Surrender charges and market value adjustments can still apply to withdrawals during the surrender period.
  • Fixed indexed annuities credit interest based on an index, up to a cap or participation rate, and credited interest is typically 0% in a down index year. Credited interest usually locks in each contract year, but rider fees, surrender charges or an adjustment can still reduce the value.
  • Income riders and income annuities can provide income the client can’t outlive, so less has to come from the market in a bad year.

There is no standard allocation. Any recommendation has to be based on the client’s income needs, liquidity, time horizon and other assets, and documented under best-interest standards. Guarantees depend on the issuing company’s financial strength and claims-paying ability, and withdrawals above the free amount during the surrender period can carry surrender charges.

Get the Annuity 101 cheat sheet

Our free Annuity 101 cheat sheet for agents includes this example, 11 conversation openers and an intake checklist. You can also watch Agent Annuity 101 on YouTube. When a client is ready, send us the basics through the annuity quote request and we’ll design the case with you. See all the annuities we place on our annuities page.

Frequently asked questions

What is sequence of returns risk?

It is the risk that market losses come early in retirement, while withdrawals are being taken. Two retirees with the same average return can have very different results depending on the order of the returns.

When does sequence of returns risk matter most?

In the years just before and just after retirement, when the balance is usually at its largest and withdrawals are starting.

Does a good average return protect against it?

No. Two retirees with the same average return can get very different results if one of them takes losses early, while withdrawals are being made.

How can an annuity help with sequence of returns risk?

Fixed, multi-year guaranteed and fixed indexed annuities aren’t invested directly in the market, so money placed in one isn’t sold at a loss after a market drop. Surrender charges, adjustments and rider fees still apply, and guarantees depend on the insurer. An income rider or income annuity can also cover part of a client’s income.

General information, not tax or legal advice. Annuities are not bank deposits and are not FDIC-insured. Guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Product features, caps and rates vary by carrier, contract and state.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-10-14

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.

How to Bring Up Annuities With Clients: 11 Conversation Starters for Agents

Insurance advisor talking with a retired couple at a table in a bright office

Easy ways to bring up annuities with clients don’t lead with the annuity. Ask about the retirement worries they already have, like running out of money, a market drop right before retirement or paying for care, and listen for money that is sitting idle or exposed to risk. Below are the four steps and 11 conversation starters from our Annuity 101 training for agents.

Key takeaways

  • Lead with the client’s retirement concerns, never with a product.
  • Listen for idle or at-risk money: CDs, savings, bonds, old 401(k)s and IRAs no one is managing.
  • There is no standard allocation. Recommend only what fits the client’s goals, liquidity and time horizon, and document why.
  • A MYGA next to a CD is an easy first conversation, as long as you explain the trade-offs.
  • You don’t need to be the annuity expert. Open the door and bring SRS in to design the case.

The four-step annuity conversation

Every opener below fits into the same simple process. It is the one we teach in our Annuity 101 cheat sheet for agents.

  1. Ask what they want. Where is the money now, and what does retirement income look like?
  2. Listen for idle or at-risk money. CDs, savings, bonds, T-bills, old 401(k)s and IRAs no one is managing.
  3. Fit it to the client. Recommend only what fits their goals, liquidity and time horizon, documented as a best-interest recommendation.
  4. Bring us in. Tim joins the call to design the case with you.

11 annuity conversation starters

Start with retirement income

1. The two questions for every client. Most people have never had anyone walk them through this.

“How much guaranteed lifetime income do you have, money that pays no matter how long you live?” Then: “Has anyone ever walked you through the risks in retirement?”

2. Running out of money. Longevity risk means living longer than the money lasts.

“How confident are you that your savings will last as long as you do?”

3. Keeping their lifestyle. The go-go, slow-go and no-go years of retirement each cost something different.

“What do your go-go years look like: travel, family, hobbies? Do you have the income to keep that up through all of retirement?”

Talk about market risk

4. Getting down the mountain. Most advisors focus on the climb, the years of saving. Far fewer talk about the way down, when withdrawals start.

“You’ve done a great job climbing the mountain. Has anyone talked to you about how to get down it safely, once the withdrawals start?”

5. Loss hurts. A 20% loss needs a 25% gain just to get back to even, and a 50% loss needs a 100% gain.

“If the market dropped 20% the year you retire, you’d need a 25% gain just to get back to even. How much of your retirement money is protected from that?”

6. Sequence of returns. Two retirees can earn the same average return and get very different results, depending on when the bad years come. We explain it with a simple example in Sequence of returns risk: how to explain it to clients.

“No one controls what the market does in their first few years of retirement. Can I show you why the order of returns matters as much as the average?”

Find the safe money

7. The CD conversation. Banks email CD rates to their customers every week. A side-by-side helps the client weigh taxes, access and who stands behind the guarantee. See MYGA vs. CD for the full comparison.

“When your CD renews, would you like to compare it with a fixed annuity that guarantees a rate for a set term and defers tax on the interest? Each has trade-offs.”

8. Index-linked interest. Some clients want a chance at market-linked interest but don’t want their credited interest to go below zero. Fixed indexed annuities offer that structure, though they aren’t the right middle ground for everyone: interest linked to an index, with a floor on credited interest, but also caps, fees and a surrender period.

“Would you like to look at an option where interest is linked to a market index, but a down year credits zero instead of a loss? There are trade-offs, like caps and a surrender period.”

Income, care and the advisor objection

9. Income for life. An actual SRS client example: replacing an older annuity added about $7,500 a year in lifetime income. Results vary, and every replacement needs a full comparison of what the client gives up and gains.

“Do you have income you can’t outlive, beyond Social Security? If you own an older annuity, let’s review what it guarantees today and compare your options.”

10. Healthcare and long-term care. Care is one of the biggest costs in retirement, and some clients won’t buy stand-alone long-term care insurance.

“If you needed care someday, which money would pay for it?”

11. “My advisor handles my money.”

“I’m not asking you to move what your advisor manages. Let’s look at whether any part of your money needs guarantees, based on your income needs and how much you need to keep available.”

There is no standard allocation. The right amount, if any, depends on the client’s income needs, liquidity, time horizon and other assets, and the reasons belong in your best-interest documentation.

Who to call first

Look through your book for clients who are 59½ or older (or close to it) with a lump sum in CDs, savings or an old 401(k) they won’t need soon, anyone two to ten years from retirement, and anyone who has told you the market makes them nervous. The taxable part of an annuity withdrawal before age 59½ can be subject to a 10% IRS additional tax unless an exception applies (IRS Topic 558). That is separate from the contract’s free-withdrawal allowance, which only avoids the insurer’s surrender charge.

What to gather before you call SRS

Send us the client’s age and state (and their spouse’s age if income should cover both), the amount, where the money sits now, whether it is qualified (IRA, 401(k), 403(b)) or non-qualified, how much they need to keep available, and what they want the money to do. If an existing annuity would be replaced, include its statement and contract, surrender schedule, any market value adjustment and the guarantees or riders that would be given up. With that, we can shop carriers and check suitability in one pass. The full intake checklist is in the free cheat sheet, and you can send a case through our annuity quote request.

Get the full Annuity 101 cheat sheet

The Annuity 101 cheat sheet puts all of this on three pages: the annuity types in 60 seconds, all 11 openers, what to listen for, an intake checklist and compliance guardrails. You can also watch Agent Annuity 101 on YouTube or see every product we place on our annuities page. New to SRS? Get contracted here.

Frequently asked questions

Where do many agents start with annuities?

Many agents start with a multi-year guaranteed annuity (MYGA). It has three moving parts (how long, what rate, what access), and most clients already understand CDs, so the comparison is easy to explain. Whether it fits depends on the client.

How much of a client’s money should go into an annuity?

There is no standard percentage. Under the NAIC best-interest model regulation, as adopted in each state, a recommendation has to be based on the client’s own financial situation, liquidity needs, time horizon and goals, and the reasons have to be documented.

When is an annuity a poor fit?

When the client may need most of the money soon, has no emergency fund outside the annuity, or is only chasing returns. Surrender charges apply to withdrawals above the free amount during the surrender period.

What do I need before I can sell annuities?

Typically annuity CE, then the carrier appointment, then the carrier’s product training, then the application. Requirements vary by state and carrier, and SRS can help with contracting and appointments.

Sources: IRS Topic 558: additional tax on early distributions

General information, not tax or legal advice. Annuities are not bank deposits and are not FDIC-insured. Guarantees are backed by the financial strength and claims-paying ability of the issuing insurance company. Product features, caps and rates vary by carrier, contract and state.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-10-14

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.

Declined for Life Insurance? What to Do Next

Couple at a kitchen table reviewing papers with an insurance advisor on a video call

Being declined for life insurance by one company does not mean you cannot get coverage. Each insurer judges health conditions differently, so the best next step is to find out why you were declined, gather your medical details and have a specialist shop your case before you apply again.

Key takeaways

  • A decline applies to one insurance company and one application, not to every carrier.
  • Find out the reason first. It decides which carriers are worth approaching.
  • An informal pre-screen lets carriers look at your case before you file a new formal application.
  • If traditional coverage is not available yet, coverage through work or a simplified or guaranteed issue policy may help in the meantime.

Why one decline is not the final answer

Every insurance company writes its own underwriting guidelines. A condition one carrier declines, another may accept, sometimes with a higher premium (a “table rating”) and sometimes at standard rates. Timing matters too: a carrier that says no during treatment may say yes once your health has been stable for a while.

For real examples, see how a client was approved at standard rates after three carrier declines and another after hepatitis C and two carrier setbacks.

Step 1: Find out why you were declined

Ask the agent who submitted your application, or the insurance company, what drove the decision. Common reasons include a recent diagnosis, abnormal lab results, certain medications, height and weight, driving history or missing medical records. The reason tells a specialist which carriers are most likely to view your history favorably.

It also helps to check your MIB record. Insurers that belong to MIB share coded information from applications for individually underwritten life and health insurance. MIB says you can request a free copy of your MIB Consumer File, if one exists, once a year, and it explains how to correct anything that is inaccurate. You will only have a file if you applied for that kind of coverage in the last seven years.

Step 2: Do not rush into another formal application

Applying to company after company on your own can add to your record without getting you closer to a yes. A better path is an informal inquiry, sometimes called a pre-screen: a specialist sends a summary of your health history to the carriers most likely to approve it and asks how each would view it. You apply formally only after you know where you stand.

This is the core of impaired risk life insurance, and it is how a specialist can often find coverage after a decline.

Step 3: Gather your medical details

Underwriters decide based on the facts in front of them. The more complete the picture, the better your chances. Have these ready:

  • The diagnosis, when it was made and your treatment so far
  • Current medications and dosages
  • Recent lab results and readings (for example, A1C or blood pressure, if they apply to you)
  • Your doctors’ names and the dates of recent visits
  • Anything that shows improvement: stable readings, weight loss, or time since surgery or treatment

Don’t have all the details? That’s fine. If you don’t have everything yet, we can start with a conversation and go over what you do have.

The details that help most show how well a condition is controlled today, not just that you have it.

Advisors can find more on this in what to include in a health history.

Step 4: Know the difference between declined and postponed

A postponement means “not right now.” Insurers often postpone after a recent surgery, a new diagnosis or during active treatment, because they want to see how things turn out. Ask how much time the insurer wants to see, then set a date to revisit. See how one postponed anemia case was later approved at standard rates.

Step 5: Options if traditional coverage is not available

If fully underwritten coverage is out of reach for now, these options may help bridge the gap:

  • Group life insurance through work. It often requires no medical questions when you enroll during an open enrollment period.
  • Simplified issue life insurance. Health questions but no medical exam, usually for smaller amounts.
  • Guaranteed issue life insurance. No health questions. Amounts are usually small, it costs more for the coverage you get, and many policies limit the full benefit in the early years.
  • Final expense coverage. Smaller policies meant to cover funeral and end-of-life costs. See our personal planning page.

These can be a good backstop, but they are rarely the end of the road. It is worth revisiting fully underwritten coverage as your health history improves.

How SRS can help

CPS Special Risk Services has spent 50+ years helping place hard-to-place life insurance cases and works with 60+ carriers. Tim Fuller will review your health history, explain which carriers are most likely to say yes, and shop your case before you apply. There is no cost to talk with Tim, and you don’t need all your records to get started.

Talk to Tim about your situation, or learn more about impaired risk life insurance. Financial professionals with a declined client can send us the case.

Frequently asked questions

Does being declined for life insurance mean I can never get coverage?

No. A decline applies to one insurance company and one application. Other carriers may view the same health history differently, and the same carrier may look again once more time has passed.

Will other insurers know I was declined?

Many applications ask whether you have ever been declined, so answer honestly. Insurers that belong to MIB may also see coded information from your earlier application. You can request your own MIB Consumer File to see what it contains.

How long should I wait before applying again?

It depends on the reason. If you were postponed, ask the insurer how much time it wants to see. If you were declined, have a specialist pre-screen your case first so your next application goes to a carrier that is likely to say yes.

Is guaranteed issue life insurance a good option?

It can be when other doors are closed, because there are no health questions. Coverage amounts are usually small, it costs more for the coverage you get, and many policies limit the full benefit in the early years, so compare the details before you buy.

Sources: MIB: request your MIB Consumer File

General information, not medical, legal or tax advice. Underwriting decisions are made by each insurance company, and policy features and availability vary by carrier and state.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-10-13

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.

Worried About a Market Drop Before Retirement? How the IUL Floor Works

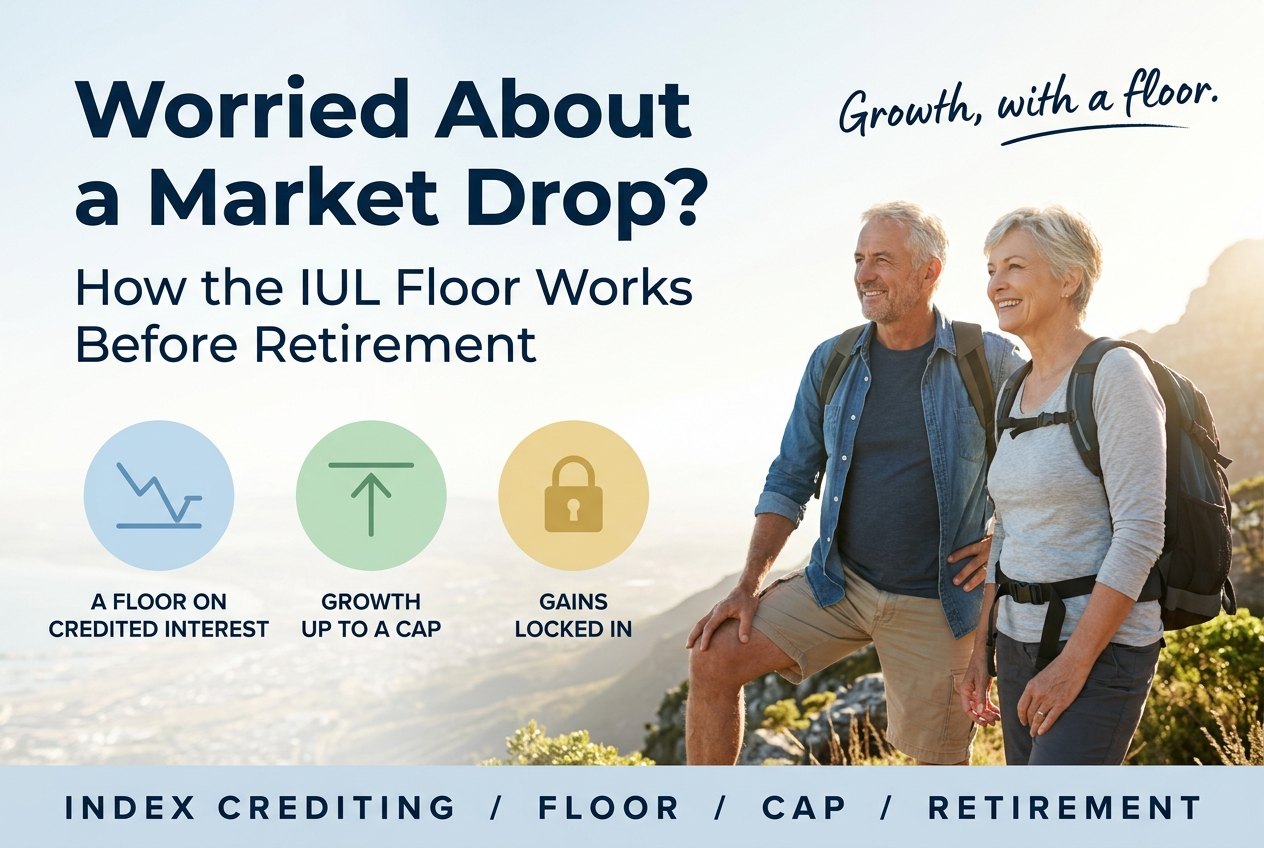
Couple in their late 50s hiking at a mountain overlook, under the title Worried About a Market Drop? How the IUL Floor Works Before Retirement

Indexed universal life (IUL) credits interest based on a market index, with a floor, usually 0%, so the interest credited in a bad year is never negative. In return, the upside is limited by a cap or participation rate. The floor protects credited interest, not the whole account: policy charges still come out every year.

Key takeaways

  • A market loss in the years just before or after retirement can do outsized damage because withdrawals lock it in.
  • IUL credits zero, not a loss, in a negative index year; gains are credited up to a cap or participation rate.
  • Policy charges still apply, so cash value can go down in a zero-credit year.
  • Caps and participation rates are not guaranteed and can change, within contract minimums.

Why a loss near retirement hurts more

Planners call it sequence-of-returns risk. If the market falls early in retirement while you are withdrawing money, you sell more shares to get the same income, and those shares are not there when the market recovers. The same average return can leave two retirees with very different outcomes depending on when the bad years land.

How IUL crediting works

Cash value is not invested in the market. The carrier credits interest based on how an index performs over a set period, usually one year, using three levers:

  • Floor: the lowest rate that can be credited, usually 0%.
  • Cap: the highest rate that can be credited for the period.
  • Participation rate: the share of the index gain that counts toward the credit.

A hypothetical example, for illustration only: with a 0% floor, a 10% cap and 100% participation, an index year of minus 15% credits 0%, an index year of plus 6% credits 6%, and an index year of plus 20% credits 10%. Credited interest is locked in each period, so a later down year does not take it back.

The floor does not make IUL an investment without risk. It means a bad market year costs you growth, not credited losses.

What the floor does not protect

  • Policy charges. Cost of insurance and other charges are deducted regardless of the index, so a zero-credit year can reduce cash value.
  • Changing caps. Carriers can lower caps and participation rates, subject to guaranteed minimums in the contract.
  • Illustrations. Projections assume a rate that may not happen. Ask to see a conservative scenario.

Where IUL fits in a retirement plan

IUL is best used as one bucket alongside retirement accounts, not instead of them. Some retirees draw from cash value in years when the market is down, which gives their investment accounts time to recover. Others use it for tax-free income to manage their tax bracket.

It works best when it is funded for years before retirement. Someone who needs the money within 10 to 15 years, or who cannot fund a policy consistently, is usually better served by other tools.

Frequently asked questions

Can my IUL lose value?

Yes. The floor applies to credited interest, not to the account. Policy charges are deducted every year, so cash value can decline in a year with little or no credited interest.

Are caps guaranteed?

No. Current caps and participation rates can change. The contract states the guaranteed minimums.

Is my money invested in the stock market?

No. The index is only used to calculate the interest credited. Your cash value is not invested in the index.

Is IUL better than an annuity for downside protection?

They solve different problems. A fixed indexed annuity is built for retirement income and has no death benefit or cost of insurance; IUL adds life insurance and tax-free access through loans.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.

Maxed Out Your 401(k)? How High Earners Use Indexed Universal Life

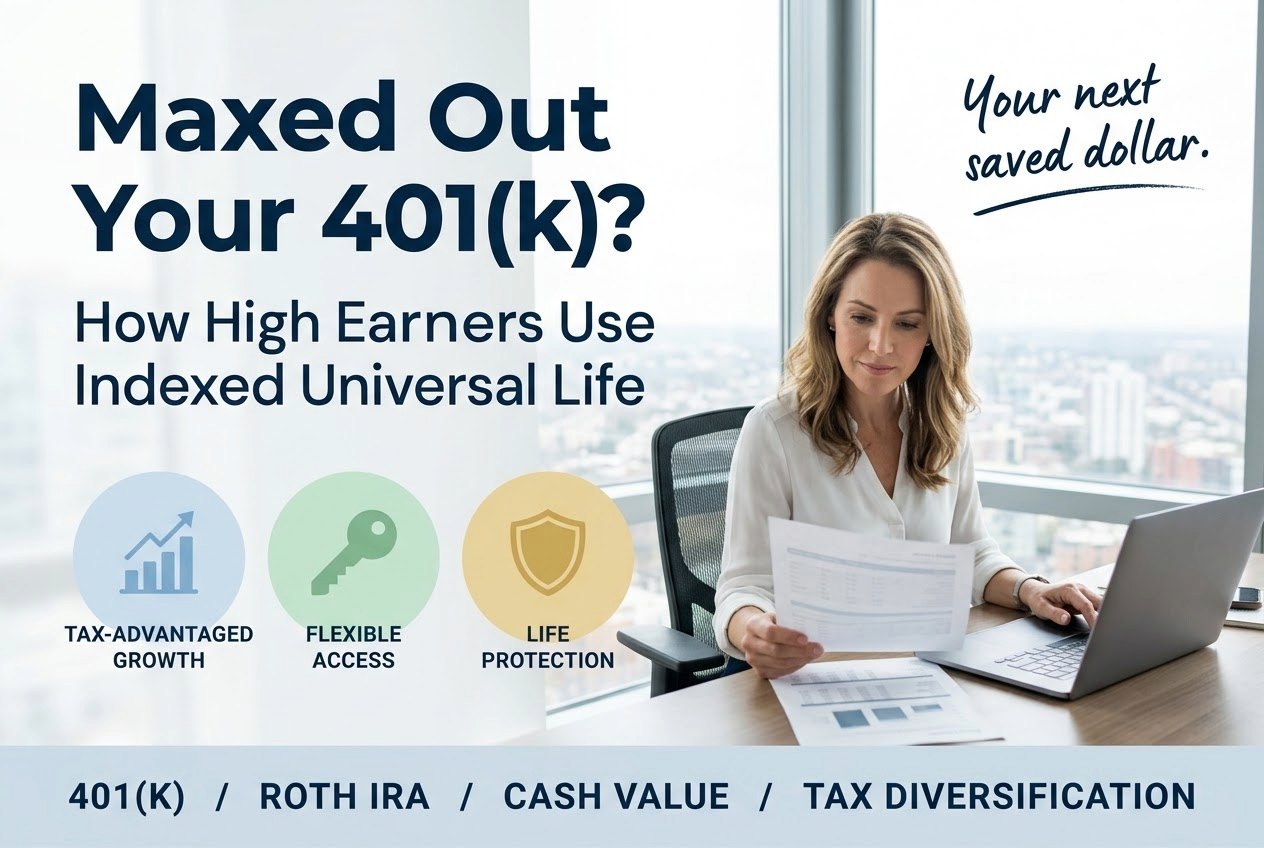
Professional woman reviewing documents at a desk with a city view, under the title Maxed Out Your 401(k)? How High Earners Use Indexed Universal Life

Once a high earner has maxed out their 401(k) and earns too much to contribute directly to a Roth IRA, a well-funded indexed universal life (IUL) policy is one more place to save with tax advantages. There are no IRS income limits on who can buy one, growth is tax-deferred, and money can be reached tax-free through policy loans when the policy is designed and kept in force correctly.

Key takeaways

  • In 2026 the 401(k) employee limit is $24,500, and direct Roth IRA contributions phase out between $153,000 and $168,000 (single) or $242,000 and $252,000 (married filing jointly).
  • IUL premiums are limited by life insurance tax rules (the MEC limits), not by your income.
  • Money comes out through withdrawals up to what you paid in, then policy loans.
  • It is life insurance first: there are policy costs, and it works best over 15 years or more.

The gap high earners run into

For 2026 the IRS lets employees defer $24,500 into a 401(k), 403(b) or most 457 plans, plus catch-up contributions if they are 50 or older. Direct Roth IRA contributions phase out between $153,000 and $168,000 of modified adjusted gross income for single filers and between $242,000 and $252,000 for married couples filing jointly.

Above those levels, the remaining options are a backdoor Roth IRA, a taxable brokerage account, a deferred compensation plan if the employer offers one, or cash value life insurance. Each has a place. IUL appeals to people who also need life insurance and want tax-free income later.

How IUL fills the gap

An IUL policy builds cash value that is credited interest based on a market index, with a floor that keeps credited interest from going below zero and a cap or participation rate on the upside. The cash value grows tax-deferred.

How much you can put in is set by the tax code’s life insurance rules (sections 7702 and 7702A), which tie premiums to the death benefit. There is no income test. A policy funded too quickly becomes a modified endowment contract (MEC), which makes loans and withdrawals taxable first, so accumulation designs are built to stay just under that line.

For many high earners the question is not whether to save more. It is where the next saved dollar will be taxed least.

How the money comes out

  • Withdrawals up to your basis (the premiums you paid) are generally not taxable.
  • Policy loans after that are generally not taxable while the policy stays in force and is not a MEC.
  • The death benefit passes to beneficiaries generally free of income tax.

The catch is that loans accrue interest and reduce the death benefit. If a policy lapses with a large loan outstanding, the gain can become taxable all at once. Income plans need to leave enough value in the policy to keep it in force for life.

What it costs, and who it is not for

IUL has cost of insurance, policy charges and surrender charges in the early years. A taxable brokerage account has no insurance costs, so IUL only makes sense when the tax benefits and the death benefit are worth those charges to you. It is usually not a fit for money you may need within 10 to 15 years, for anyone who cannot fund it consistently, or for someone looking only for investment returns.

Designing it well

Accumulation IUL is usually designed with the smallest death benefit the tax rules allow for the planned premiums, an increasing death benefit option while you are funding it, and a switch to a level death benefit before income begins. Ask to see illustrations at more than one crediting rate, including a conservative one.

Frequently asked questions

Is IUL a replacement for a Roth IRA?

No. It is a complement. Many high earners do a backdoor Roth IRA first, then use IUL for additional savings, especially if they also need life insurance.

What is a MEC?

A modified endowment contract is a life insurance policy funded faster than the tax code allows. It loses tax-free access: loans and withdrawals are taxed as income first and may carry a 10% penalty before age 59½.

Are there income limits to buy IUL?

No. Premium limits come from the life insurance tax rules and the death benefit, not your income. Carriers do underwrite coverage amounts based on income and net worth.

How long should I plan to fund it?

Most accumulation designs assume funding for at least 7 to 10 years and holding the policy 15 years or more before taking income.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

Sources: IRS: 2026 401(k) and IRA limits

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.

Do Policy Loans Count Toward IRMAA or Social Security Taxes?

Retired couple reviewing paperwork and a laptop at a dining table, under the title Do Policy Loans Count Toward IRMAA?

Generally, no. Loans from a life insurance policy that is not a modified endowment contract and stays in force are not taxable income. That means they do not count in the modified adjusted gross income Medicare uses for IRMAA surcharges, or in the combined income that decides how much of your Social Security is taxed.

Key takeaways

  • For 2026, IRMAA surcharges on Medicare Part B and Part D begin above $109,000 of MAGI for individuals and $218,000 for joint filers.
  • Up to 85% of Social Security benefits can be taxed once combined income passes $34,000 (single) or $44,000 (joint).
  • Policy loans do not show up in either calculation; 401(k) and IRA withdrawals do.
  • The policy must stay in force: a lapse with a loan outstanding can create taxable income.

How IRMAA works

Medicare’s income-related monthly adjustment amount (IRMAA) adds a surcharge to Part B and Part D premiums for people with higher income. For 2026 the standard Part B premium is $202.90 a month, and surcharges start when modified adjusted gross income is above $109,000 for individuals or $218,000 for married couples filing jointly. Medicare uses your tax return from two years earlier, so 2024 income sets 2026 premiums.

Because the brackets are cliffs, one extra dollar of income can raise premiums for the whole year. A large IRA withdrawal, a Roth conversion or a capital gain can push someone over.

How Social Security is taxed

The IRS looks at your combined income: adjusted gross income, plus nontaxable interest, plus half of your Social Security benefits. For single filers, up to 50% of benefits can be taxed above $25,000 and up to 85% above $34,000. For joint filers, the levels are $32,000 and $44,000. These thresholds are not indexed for inflation, so more retirees cross them every year.

Every dollar of retirement income is taxed somewhere. The planning question is which bucket it comes from, and in which year.

Where policy loans fit

A policy loan is a loan against your cash value, not income, so it is not reported on your tax return. Used alongside retirement account withdrawals, it lets a retiree take the income they need while keeping reported income under an IRMAA bracket or a Social Security threshold.

  • Withdrawals up to your basis (premiums paid) are also generally not taxable.
  • Roth IRA qualified distributions are tax-free too; cash value is another source alongside them.
  • Traditional IRA and 401(k) withdrawals, pensions and most annuity income are taxable and count toward both calculations.

The catches

Policy loans accrue interest, and they reduce the death benefit. If a policy lapses or is surrendered with a loan outstanding, the gain above your basis becomes taxable in that year, which could cause the very IRMAA and tax problem you were avoiding. Income from a policy needs to be planned so the policy stays in force for life.

This also only works if the policy was funded years earlier. It is a strategy to set up in your 40s and 50s, not the year you retire.

Frequently asked questions

Are life insurance withdrawals taxable?

Withdrawals up to your basis, the premiums you paid, are generally not taxable. Amounts above basis are taxable unless taken as a policy loan.

Do I pay interest on a policy loan?

Yes. Policy loans accrue interest. Some policies offer fixed-rate loans and others variable or indexed loans, each with different risks.

Does this work with a MEC?

No. Loans and withdrawals from a modified endowment contract are taxed as income first, so they can count toward IRMAA and Social Security taxation.

Which year’s income sets IRMAA?

Medicare generally uses your tax return from two years earlier. For 2026 premiums, that is your 2024 return.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

Sources: CMS: 2026 Medicare Parts A & B premiums · SSA: income taxes on benefits

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.

Life Insurance vs. a 529 Plan: Saving for a Child Who May Not Go to College

Parent and teenage son talking at a kitchen table with a laptop, college brochures and a toolbox, under the title Life Insurance vs. a 529 Plan: Saving for a Child Who May Not Go to College

For most families, a 529 plan is the most efficient way to save for college. Cash value life insurance appeals to parents who want flexibility if their child chooses a trade, starts a business or skips college, and who also want the plan protected if a parent dies. Many families use both.

Key takeaways

  • 529 earnings are tax-free when spent on qualified education; earnings used for other purposes are taxed and usually hit with a 10% additional tax.
  • Cash value life insurance can be used for anything, through withdrawals and policy loans, with no education requirement.
  • Cash value is generally not reported as an asset on the FAFSA.
  • Life insurance needs years of consistent funding before the cash value is meaningful.

Where a 529 plan shines

A 529 plan is purpose-built for education. Growth is tax-deferred, withdrawals for qualified education expenses are tax-free, and many states give a state income tax deduction for contributions. Under SECURE 2.0, a 529 that has been open at least 15 years can also roll up to $35,000, over the beneficiary’s lifetime, into a Roth IRA for that beneficiary, subject to annual Roth limits.

The trade-off is the restriction. Earnings withdrawn for non-qualified expenses are subject to income tax and, in most cases, a 10% additional tax. That additional tax is waived up to the amount of a tax-free scholarship, but the income tax still applies.

Where cash value life insurance fits

A permanent policy, such as indexed universal life or whole life, builds cash value that can be reached through withdrawals and policy loans for any purpose. If your child becomes an electrician, a business owner or a missionary instead of a college student, the money is still usable without a penalty.

There are two common designs. A policy on a parent protects the plan: if the parent dies, the death benefit can fund the goal. A policy on the child builds a very long runway and gives the child lifelong coverage, and it is often started by grandparents.

The question is not which account is better. It is how sure you are that the money will be spent on college.

Side by side

529 planCash value life insurance
Best forMoney you are confident will pay for educationMoney that may be used for education or something else
Tax on growthTax-deferred; tax-free for qualified educationTax-deferred; tax-free access through loans and withdrawals to basis if designed and kept in force correctly
Non-education useEarnings taxed plus, usually, a 10% additional taxNo penalty; loans reduce the death benefit
FAFSAParent-owned 529 is reported as a parent assetGenerally not reported
Death benefitNoneYes
Early-year costsLowHigher; surrender charges in early years

The honest trade-offs

Life insurance has costs a 529 does not: cost of insurance, policy charges and surrender charges in the early years. That means cash value grows slowly at first and needs roughly 10 to 15 years or more to work well. If college is only a few years away, a 529 or a savings account is usually the better tool.

Loans and withdrawals also reduce the death benefit, and a policy that lapses with a loan outstanding can create a tax bill. The policy needs to be designed and monitored with the goal in mind.

Using both

Many families put their base college savings in a 529, then add a cash value policy for flexibility and protection. That way the education dollars get the best tax treatment, and the family still has money that can go anywhere life leads. See how SRS approaches college funding.

Frequently asked questions

Is cash value life insurance counted on the FAFSA?

Cash value life insurance is generally not reported as an asset on the FAFSA. Schools that use the CSS Profile may ask about it.

What happens to a 529 if my child gets a scholarship?

You can withdraw up to the scholarship amount without the 10% additional tax, but the earnings portion is still subject to income tax.

Can I use a 529 and life insurance together?

Yes. Many families use a 529 for money they are confident will go to education and cash value life insurance for flexibility and protection.

How long before the cash value is useful?

It depends on the design and funding, but cash value life insurance usually needs 10 to 15 years or more to build meaningful value.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

Sources: IRS Publication 970 (529 plans) · Saving for College: assets and financial aid

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.

Why Grandparents Buy Life Insurance for Their Grandchildren

Grandparents helping their young grandson plant a tree in the backyard, under the title Why Grandparents Buy Life Insurance for Their Grandchildren

Grandparents buy permanent life insurance on a grandchild to give a gift that keeps growing for decades: coverage the child keeps for life, plus cash value that can later help with college, a first home or a business. The grandparent owns and pays for the policy, so they stay in control until they decide to hand it over.

Key takeaways

  • The grandparent is usually the owner and payor; a parent or guardian normally signs the application for a minor.
  • Starting young means low insurance costs and many decades for cash value to grow.
  • The grandchild keeps coverage for life, no matter what happens to their health later.
  • Handing the policy to the grandchild later counts as a gift, so plan the timing with a tax advisor.

What grandparents are really buying

Most grandparents who ask about this are not worried about a death benefit on a child. They want to leave something meaningful that outlasts them, and they would rather not hand an 18-year-old a check. A permanent policy lets them do both: it builds value slowly and quietly, and it arrives with guardrails.

  • A head start. Cash value that can grow for 20, 30 or 50 years before anyone needs it.
  • Lifelong insurability. Coverage that stays in place even if the grandchild later develops diabetes, heart disease or another condition that makes insurance expensive or unavailable.
  • A legacy with a story. Many grandparents hand the policy over at a milestone, such as graduation, a wedding or age 30, along with a letter about why they started it.

How the policy is set up

Three roles matter. The owner controls the policy and pays the premiums; this is usually the grandparent. The insured is the grandchild. The beneficiary, who receives the death benefit, is often a parent while the child is young.

Name a successor owner too, usually a parent. If the grandparent dies before handing the policy over, the successor owner takes control and the policy keeps going instead of ending up in the grandparent’s estate paperwork.

When the grandchild is ready, ownership can be transferred to them. That transfer is a gift. In 2026 the IRS annual gift tax exclusion is $19,000 per recipient, and the value of a transferred policy is generally measured by its value at the time of transfer, not the premiums paid. A tax advisor can help time it.

The most valuable part of the gift may be insurability: coverage locked in before the grandchild has any health history at all.

Whole life or indexed universal life?

Whole life has guaranteed cash value growth and fixed premiums. It suits grandparents who want predictability and a set payment schedule.

Indexed universal life (IUL) credits interest based on a market index, with a floor that keeps credited interest from going below zero, and it allows flexible premiums. It suits grandparents who want more growth potential and are comfortable with non-guaranteed crediting. Policy charges apply to both designs, so either one needs to be funded as planned.

What the money can do later

Once the grandchild owns the policy, they can use the cash value through withdrawals and policy loans for anything: tuition, a down payment, starting a business, or leaving it alone to keep growing. Unlike a 529 plan, there is no penalty if the money is not spent on education.

Cash value life insurance is also generally not reported as an asset on the FAFSA. Some private colleges that use the CSS Profile ask about it, so check with the schools on the list.

Limits and things to watch

  • Coverage limits. Carriers cap how much insurance a child can have, often based on how much coverage the parents carry.
  • Early years. Surrender charges and policy costs are highest in the first 10 to 15 years, so this works best as a long-term gift.
  • Funding. Paying in too much too fast can turn the policy into a modified endowment contract (MEC), which changes how withdrawals and loans are taxed. The policy should be designed to stay under those limits.
  • Consent. Rules on who can insure a child vary by state and carrier.

Frequently asked questions

Do the parents need to agree?

Usually yes. Most carriers require a parent or legal guardian to sign the application for a minor, and rules vary by state.

Can I buy a policy for each grandchild?

Yes. Each grandchild gets a separate policy, and each one is subject to the carrier’s coverage limits for children.

What happens if I die before I hand the policy over?

If you name a successor owner, usually a parent, that person takes over ownership and the policy continues.

Does the cash value count against financial aid?

Cash value life insurance is generally not reported as an asset on the FAFSA. Some schools that use the CSS Profile may ask about it.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

Sources: IRS: gift tax FAQs · Saving for College: assets and financial aid

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.

Death Tax Savings For The Uninsurable – A Small Balm In Gilead

Advisor and client reviewing an advanced markets estate planning strategy in a private office

When the first generation of a high-net-worth family can’t qualify for life insurance, the usual estate-tax funding playbook stalls. Here’s the structure advisors use to keep the plan moving anyway.

Key takeaways

  • When the first generation is uninsurable, insurance on the second generation — funded via generational split-dollar — can keep the estate tax plan alive.
  • The first generation lends premium dollars to a trust owning policies on the second generation; the loan is repaid only when the second-generation insureds die.
  • Because repayment is decades away, the loan avoids using lifetime gift-tax exemption and can qualify for a valuation discount in the first generation’s estate.

Generational split-dollar lets a family fund estate-tax liquidity through the second generation when the first generation can’t qualify for coverage at any price.

The problem when the first generation is uninsurable

Estate tax planning for wealthy families usually follows two steps: reduce the anticipated tax bill with every workable strategy, then insure against what’s left with life insurance on the first-generation client, typically a grandparent. That plan breaks down when the grandparent turns out to be a medical decline and can’t get coverage at any price.

Shifting the insurance to the next generation

Most tax and legal advisors point to the same fallback: insure the second generation instead, so there’s liquidity to cover estate tax when the second generation’s wealth eventually passes to the third. The structure that makes this work is often called generational split-dollar.

How the loan structure works

The first generation lends the premium dollars to the owner of the policies on the second generation, usually an irrevocable trust whose beneficiaries are generations two and three. The note is repayable only when the second-generation insureds die, often decades away. That timing matters for two reasons: the loan doesn’t require using any of the first generation’s lifetime gift-tax exemption to cover premiums, and when the note’s value later lands in the first generation’s estate, it can qualify for a meaningful valuation discount since repayment is so far out.

What the Levine case confirmed

Generational split-dollar drew scrutiny for years after some unfavorable rulings. That changed with the Tax Court’s decision in Levine v. Commissioner, which upheld a $2,300,000 valuation on a $6,500,000 note, saving the estate over $1,500,000 in estate taxes, and gave attorneys a workable blueprint for drafting these arrangements.

How to use this with clients

This is a fit for families where the first generation is uninsurable and there’s still a meaningful anticipated estate tax bill at the second generation’s death. Underwriting the second generation is more involved, since it requires showing the carrier a credible path to the anticipated inheritance, but it’s often the only way to keep the estate-tax funding plan alive once the first generation can’t qualify.

If you have a client whose estate plan depends on insurance the first generation can no longer qualify for, that’s a case we can help you work through.

Frequently asked questions

What is generational split-dollar?

It’s a strategy where the first generation lends premium dollars to a trust that owns life insurance on the second generation, with the loan repaid only at the second generation’s death. It lets a family fund estate-tax liability at the second-to-third generation transfer without using the first generation’s gift-tax exemption.

Does this only apply when the first generation is uninsurable?

No. It’s most often used as a fallback when the first generation can’t qualify for coverage, but it can also make sense when the first generation is insurable and there’s still a substantial estate tax expected at the second generation’s death.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-23

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency) connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners — with the impaired-risk and complex-case expertise to place business other IMOs and BGAs turn away.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.