
Call 303-309-3471 Advisors: get contracted with SRS →Get a Quote

How Business Owners Use Indexed Universal Life

Two business owners reviewing plans on a tablet in a manufacturing workshop, under the title How Business Owners Use Indexed Universal Life

Business owners use indexed universal life (IUL) for three main jobs: rewarding and keeping key employees through executive bonus plans, protecting the business if a key person dies, and funding buy-sell agreements. The cash value can also become supplemental retirement money for the owner or the employee later.

Key takeaways

  • Executive bonus (Section 162): the business pays the premium as a bonus, generally deductible as compensation, and the employee owns the policy.
  • Key person: the business owns the policy and receives the death benefit; premiums are not deductible.
  • Buy-sell: life insurance funds the purchase of an owner’s share at death, and cash value can help with a lifetime buyout.
  • Employer-owned policies need notice and written consent before they are issued.

Executive bonus plans (Section 162)

The business pays the premium on a policy owned by the employee and reports it as a bonus. The bonus is generally deductible to the business as reasonable compensation and taxable income to the employee; some plans add a bonus to cover that tax. The employee gets a death benefit for their family and cash value they can use later.

A restricted executive bonus adds a vesting schedule or other restrictions, so the employee has a reason to stay. It is a simple way to create “golden handcuffs” without a qualified plan.

Key person protection

If a top salesperson, engineer or co-owner dies, the business can lose revenue, credit and time. With key person coverage, the business owns the policy, pays the premium and receives the death benefit to recruit a replacement, reassure lenders and keep operating. Premiums are not deductible, and the cash value is a business asset.

Employer-owned life insurance must meet the notice and consent rules in IRC section 101(j) before the policy is issued, or part of the death benefit can become taxable. Your advisor and CPA should confirm the paperwork is in place.

For many business owners, the business is the biggest asset. Life insurance is often what makes the succession plan actually work.

Funding buy-sell agreements

A buy-sell agreement sets who buys an owner’s share, and at what price, if the owner dies, becomes disabled or leaves. Life insurance provides the money at death. In a cross-purchase plan the owners insure each other; in an entity purchase plan the business insures each owner. Cash value in an IUL can also help fund a buyout at retirement.

Retirement money for the owner

Owners who have maxed out their qualified plan sometimes use IUL as supplemental retirement savings, taking tax-free policy loans in retirement when the policy is designed and kept in force correctly. It pairs well with a business that has uneven cash flow, since IUL premiums can be flexible within limits.

See SRS business planning for key person, buy-sell, executive compensation and succession resources.

Frequently asked questions

Are life insurance premiums tax-deductible for a business?

Executive bonus premiums are generally deductible as compensation. Premiums on policies the business owns and benefits from, such as key person coverage, are not deductible.

What is a restricted executive bonus arrangement?

An executive bonus plan with a vesting schedule or other restrictions on the policy, used to encourage a key employee to stay.

Cross-purchase or entity purchase?

It depends on the number of owners, the business structure and tax goals. Work through it with your CPA and attorney.

Do employees have to consent to employer-owned life insurance?

Yes. Under IRC section 101(j), the employee must receive notice and give written consent before the policy is issued.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Protection Now, Savings Later: Why Young Families Consider Indexed Universal Life

Young family of four sitting on a hillside at sunset, with the title Protection Now, Savings Later: Why Young Families Consider Indexed Universal Life

Young families usually need a large death benefit on a tight budget, and term life is the most affordable way to cover that need. Some families add indexed universal life (IUL) on top, or instead of part of the term, to build cash value over time and get living benefits riders in the same policy.

Key takeaways

  • Start with the need: enough coverage to replace income, clear debts and fund goals like college.
  • Term life covers the biggest need for the lowest cost.
  • A smaller IUL alongside term adds cash value, lifelong coverage and optional living benefits.
  • Only add IUL if you can fund it consistently for many years.

Start with the need

The first job of life insurance for a young family is replacing income so the family can keep the home, stay on track with savings and cover childcare and college if a parent dies. A needs analysis adds up income replacement, debts, final expenses and goals, then subtracts savings and existing coverage. See how SRS approaches income replacement.

Term, permanent or both

Term lifeIndexed universal life
Cost for the same death benefitLowestHigher
How long it lastsA set term, such as 20 or 30 yearsFor life, if funded
Cash valueNoneYes, credited based on an index with a floor
Living benefits ridersAvailable on some policiesCommonly available
Best forLarge, temporary needsLifelong coverage plus long-term savings

A common blend is term for most of the need, which usually falls away as the kids grow and the mortgage shrinks, and a smaller IUL that keeps going for life and builds cash value the family can use later.

The right answer for most young families is not term or permanent. It is how much of each.

Living benefits in the same policy

Many IUL policies offer chronic, critical and terminal illness riders that let you advance part of the death benefit if you are seriously ill. For a young family, that can mean help with bills during a cancer treatment or after a stroke. These riders are not the same as disability or long-term care insurance, and terms vary by carrier.

When IUL is the wrong fit

  • The budget only covers the coverage you need, and IUL would mean buying less protection.
  • You may need the money back within 10 to 15 years.
  • You are not sure you can keep funding it. An underfunded policy can lapse.
  • Emergency savings and employer retirement matches are not in place yet.

Frequently asked questions

How much life insurance does a young family need?

A common starting point is enough to replace income for the years the family would need it, plus debts, final expenses and goals like college. A needs analysis gives a more precise number.

Can I convert term to permanent later?

Many term policies include a conversion privilege that lets you switch to permanent coverage without a new medical exam, within a set window.

Should both parents be insured?

Usually yes. A stay-at-home parent provides childcare and household work that would be expensive to replace.

Is IUL a good place for my emergency fund?

No. Cash value builds slowly and early surrender charges apply. Keep emergency savings in a bank account.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Living Benefits Riders vs. Long-Term Care Insurance: What Your Life Policy Can and Can’t Do

Adult daughter and her elderly mother looking at a tablet together on a sofa, under the title Living Benefits vs. Long-Term Care Insurance

Many indexed universal life policies include chronic, critical and terminal illness riders that let you use part of the death benefit while you are alive. They can help pay for care, but they are not long-term care insurance: benefits reduce the death benefit, may be discounted or capped, and follow the carrier’s rules. For a larger care plan, a hybrid life and long-term care policy or a traditional long-term care policy may fit better.

Key takeaways

  • Living benefits riders advance part of the death benefit if you are chronically, critically or terminally ill.
  • Chronic illness usually means needing help with two of six activities of daily living, or severe cognitive impairment.
  • Every dollar used reduces what your beneficiaries receive.
  • Long-term care insurance and hybrid policies are built for care and usually pay more for it.

What living benefits riders do

  • Terminal illness: pays part of the death benefit early if life expectancy is limited, often 12 or 24 months, depending on the carrier.
  • Critical illness: pays after a qualifying event such as a heart attack, stroke or invasive cancer.
  • Chronic illness: pays when you cannot perform two of six activities of daily living (bathing, dressing, eating, toileting, transferring, continence) or have severe cognitive impairment.

Some riders are included at no upfront charge and cost you only when used, through a discount on the benefit paid. Others carry an ongoing charge. Accelerated benefits for chronic and terminal illness are generally received free of income tax within IRS limits, but check the rider and your situation.

How they compare

Life policy with living benefits ridersHybrid life and LTCTraditional LTC insurance
Main purposeDeath benefit, with early access if illCare benefits, with a death benefit if care is not neededCare benefits
Care benefit sizeLimited to part of the death benefit; may be discountedOften a multiple of the premium; some include extended benefitsSet by the daily or monthly benefit and benefit period
If you never need careFull death benefit to heirsDeath benefit to heirsPremiums are generally not returned
UnderwritingLife underwritingLife and care underwritingCare underwriting

A living benefits rider is a safety valve on a life insurance policy. Long-term care insurance is a care plan.

Who fits which

Living benefits riders suit people who mainly need life insurance and want some protection if serious illness hits. People who are specifically planning for care costs, especially those without family who can provide care, usually get more care coverage per dollar from a hybrid or traditional long-term care policy. See the SRS long-term care guide for those options.

Questions to ask about any rider

  • Is there a charge now, or a discount when the benefit is paid?
  • What percentage of the death benefit can be accelerated, and is there an annual or lifetime cap?
  • Is the chronic illness trigger permanent or temporary? Some riders require the condition to be permanent.
  • How does using the rider affect cash value, loans and the remaining death benefit?

Frequently asked questions

Is a chronic illness rider the same as long-term care insurance?

No. A chronic illness rider advances part of your death benefit. Long-term care insurance is designed specifically to pay for care and usually provides more care benefits.

Do living benefits riders cost extra?

Some have no upfront charge and reduce the benefit when used; others have an ongoing charge. It depends on the carrier and rider.

Are accelerated benefits taxable?

Accelerated benefits for chronic and terminal illness are generally received free of income tax within IRS limits. Check with a tax advisor for your situation.

Can I have both a rider and LTC insurance?

Yes. Some people keep a life policy with riders and add a long-term care policy for their main care plan.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

What to Do With a Required Minimum Distribution You Don’t Need

Three generations of a family sharing an outdoor meal at sunset, under the title An RMD You Don’t Need? Turning Required Distributions Into a Legacy

Some retirees take their required minimum distribution, pay the tax, and use what is left to pay premiums on a permanent life insurance policy. Money they always planned to leave to family becomes a larger death benefit that heirs generally receive free of income tax. It is one of several good options for an RMD you do not need, alongside giving to charity directly from your IRA.

Key takeaways

  • RMDs start at age 73 for people born 1951 through 1959, and at 75 for people born in 1960 or later.
  • Most non-spouse heirs must empty an inherited IRA within 10 years and pay income tax on it.
  • Life insurance death benefits generally pass to beneficiaries free of income tax.
  • Coverage requires underwriting, and costs rise with age, so compare options before deciding.

Why unneeded RMDs are a problem

Once RMDs begin, you must withdraw a minimum amount from traditional IRAs and most employer plans each year and pay income tax on it, whether you need the money or not. Under SECURE 2.0 the starting age is 73 for people born from 1951 through 1959 and 75 for those born in 1960 or later.

Whatever is left in the IRA at death is not tax-free for your heirs either. Most non-spouse beneficiaries must withdraw an inherited IRA within 10 years, often during their own peak earning years, and pay income tax at their rates.

How the strategy works

  • Take the RMD as required and pay the income tax.
  • Use some or all of the after-tax amount to pay premiums on a permanent life insurance policy.
  • At death, beneficiaries generally receive the death benefit free of income tax.

For pure legacy goals, guaranteed universal life or a survivorship (second-to-die) policy on a married couple is often the most efficient. Indexed universal life or whole life fits people who also want access to cash value if plans change.

If the money is going to your children anyway, the question is how much of it the IRS takes along the way.

Other options to compare

OptionBest whenWatch for
Qualified charitable distribution (QCD)You give to charity anywayMust go directly from an IRA to a qualified charity; annual limit applies
Spend or gift itYou want to help family nowGifts above the annual exclusion need a gift tax return
Invest in a taxable accountYou want full access and flexibilityFuture growth is taxable; heirs get a step-up in basis
Fund life insuranceThe money is meant for heirs and you are insurableUnderwriting, cost at older ages, estate inclusion

Things to check first

  • Health and age. Coverage requires underwriting. SRS specializes in placing coverage for people with health conditions, but cost rises with age.
  • Estate tax. The death benefit is generally free of income tax but can be included in your taxable estate if you own the policy. Large estates often use an irrevocable life insurance trust (ILIT); talk with an estate attorney.
  • Commitment. The premium needs to be paid for the life of the policy unless it is designed with a limited pay period.

Frequently asked questions

Can I use my RMD to pay premiums directly from the IRA?

No. The RMD is distributed to you and taxed first. You then pay the premium with the after-tax money.

Do I have to be healthy to do this?

Coverage requires underwriting, but many health conditions can still be insured. Pricing depends on age and health.

Is the death benefit tax-free?

Life insurance death benefits are generally free of income tax to beneficiaries. They can be subject to estate tax if the policy is in your estate.

Is this better than a qualified charitable distribution?

They serve different goals. A QCD is best if you want to support charity; life insurance is designed to move more to your heirs.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

Sources: IRS: required minimum distribution FAQs

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Declined for Life Insurance? What to Do Next

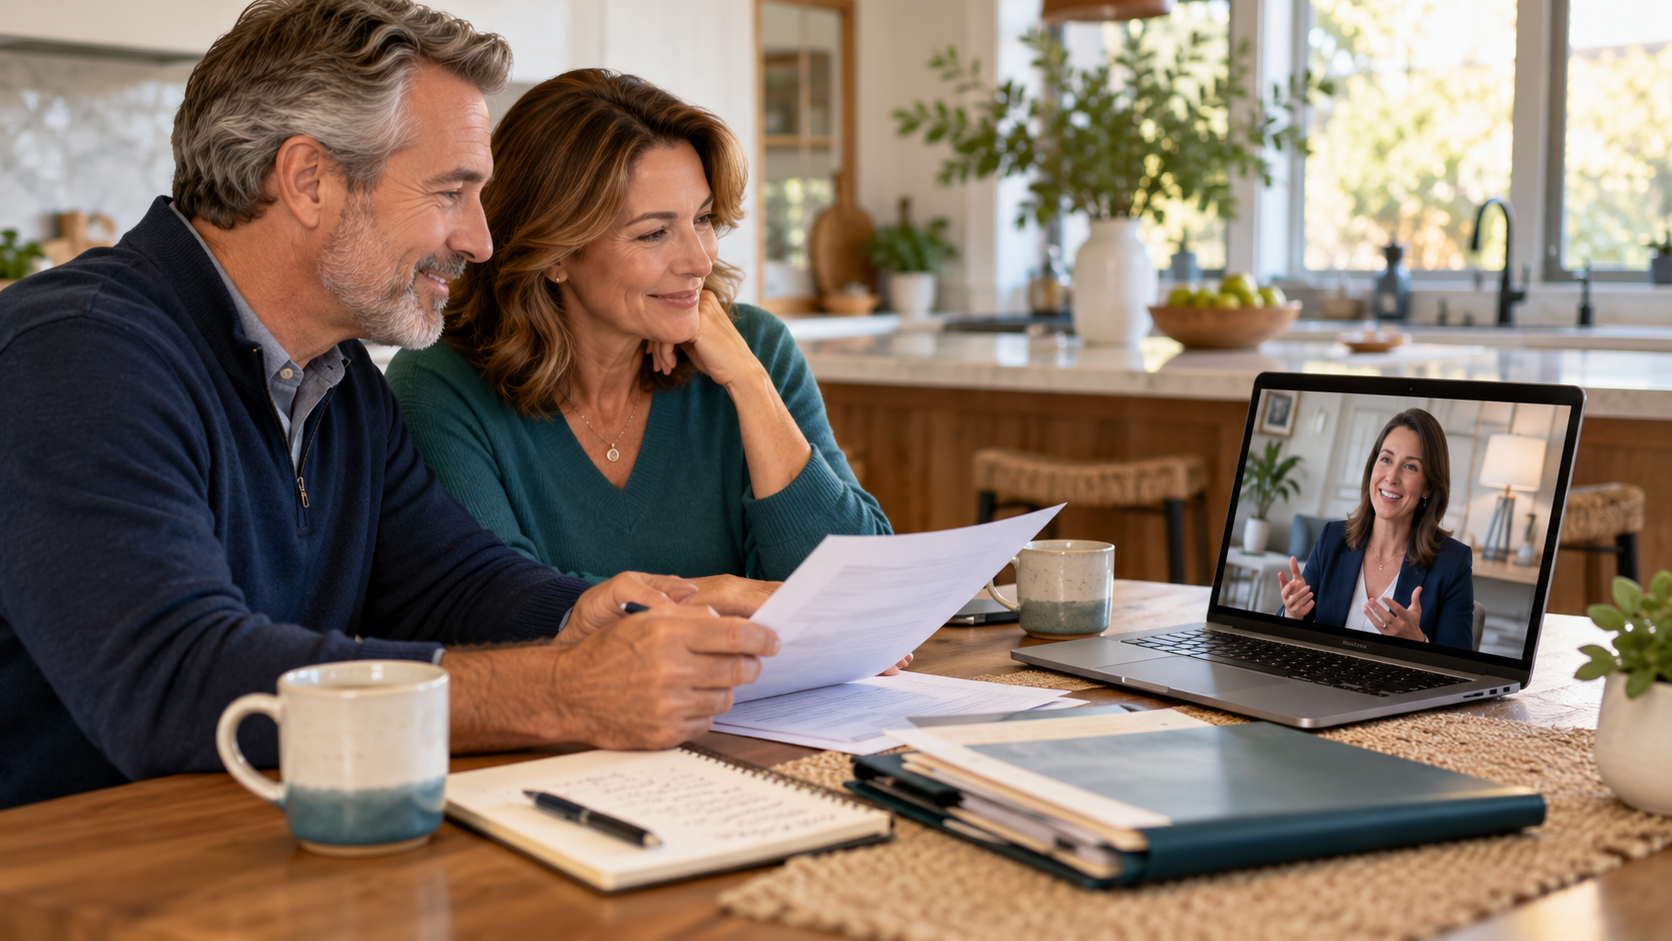
Couple at a kitchen table reviewing papers with an insurance advisor on a video call

Being declined for life insurance by one company does not mean you cannot get coverage. Each insurer judges health conditions differently, so the best next step is to find out why you were declined, gather your medical details and have a specialist shop your case before you apply again.

Key takeaways

  • A decline applies to one insurance company and one application, not to every carrier.
  • Find out the reason first. It decides which carriers are worth approaching.
  • An informal pre-screen lets carriers look at your case before you file a new formal application.
  • If traditional coverage is not available yet, coverage through work or a simplified or guaranteed issue policy may help in the meantime.

Why one decline is not the final answer

Every insurance company writes its own underwriting guidelines. A condition one carrier declines, another may accept, sometimes with a higher premium (a “table rating”) and sometimes at standard rates. Timing matters too: a carrier that says no during treatment may say yes once your health has been stable for a while.

For real examples, see how a client was approved at standard rates after three carrier declines and another after hepatitis C and two carrier setbacks.

Step 1: Find out why you were declined

Ask the agent who submitted your application, or the insurance company, what drove the decision. Common reasons include a recent diagnosis, abnormal lab results, certain medications, height and weight, driving history or missing medical records. The reason tells a specialist which carriers are most likely to view your history favorably.

It also helps to check your MIB record. Insurers that belong to MIB share coded information from applications for individually underwritten life and health insurance. MIB says you can request a free copy of your MIB Consumer File, if one exists, once a year, and it explains how to correct anything that is inaccurate. You will only have a file if you applied for that kind of coverage in the last seven years.

Step 2: Do not rush into another formal application

Applying to company after company on your own can add to your record without getting you closer to a yes. A better path is an informal inquiry, sometimes called a pre-screen: a specialist sends a summary of your health history to the carriers most likely to approve it and asks how each would view it. You apply formally only after you know where you stand.

This is the core of impaired risk life insurance, and it is how a specialist can often find coverage after a decline.

Step 3: Gather your medical details

Underwriters decide based on the facts in front of them. The more complete the picture, the better your chances. Have these ready:

  • The diagnosis, when it was made and your treatment so far
  • Current medications and dosages
  • Recent lab results and readings (for example, A1C or blood pressure, if they apply to you)
  • Your doctors’ names and the dates of recent visits
  • Anything that shows improvement: stable readings, weight loss, or time since surgery or treatment

Don’t have all the details? That’s fine. If you don’t have everything yet, we can start with a conversation and go over what you do have.

The details that help most show how well a condition is controlled today, not just that you have it.

Advisors can find more on this in what to include in a health history.

Step 4: Know the difference between declined and postponed

A postponement means “not right now.” Insurers often postpone after a recent surgery, a new diagnosis or during active treatment, because they want to see how things turn out. Ask how much time the insurer wants to see, then set a date to revisit. See how one postponed anemia case was later approved at standard rates.

Step 5: Options if traditional coverage is not available

If fully underwritten coverage is out of reach for now, these options may help bridge the gap:

  • Group life insurance through work. It often requires no medical questions when you enroll during an open enrollment period.
  • Simplified issue life insurance. Health questions but no medical exam, usually for smaller amounts.
  • Guaranteed issue life insurance. No health questions. Amounts are usually small, it costs more for the coverage you get, and many policies limit the full benefit in the early years.
  • Final expense coverage. Smaller policies meant to cover funeral and end-of-life costs. See our personal planning page.

These can be a good backstop, but they are rarely the end of the road. It is worth revisiting fully underwritten coverage as your health history improves.

How SRS can help

CPS Special Risk Services has spent 50+ years helping place hard-to-place life insurance cases and works with 60+ carriers. Tim Fuller will review your health history, explain which carriers are most likely to say yes, and shop your case before you apply. There is no cost to talk with Tim, and you don’t need all your records to get started.

Talk to Tim about your situation, or learn more about impaired risk life insurance. Financial professionals with a declined client can send us the case.

Frequently asked questions

Does being declined for life insurance mean I can never get coverage?

No. A decline applies to one insurance company and one application. Other carriers may view the same health history differently, and the same carrier may look again once more time has passed.

Will other insurers know I was declined?

Many applications ask whether you have ever been declined, so answer honestly. Insurers that belong to MIB may also see coded information from your earlier application. You can request your own MIB Consumer File to see what it contains.

How long should I wait before applying again?

It depends on the reason. If you were postponed, ask the insurer how much time it wants to see. If you were declined, have a specialist pre-screen your case first so your next application goes to a carrier that is likely to say yes.

Is guaranteed issue life insurance a good option?

It can be when other doors are closed, because there are no health questions. Coverage amounts are usually small, it costs more for the coverage you get, and many policies limit the full benefit in the early years, so compare the details before you buy.

Sources: MIB: request your MIB Consumer File

General information, not medical, legal or tax advice. Underwriting decisions are made by each insurance company, and policy features and availability vary by carrier and state.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-10-13

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Worried About a Market Drop Before Retirement? How the IUL Floor Works

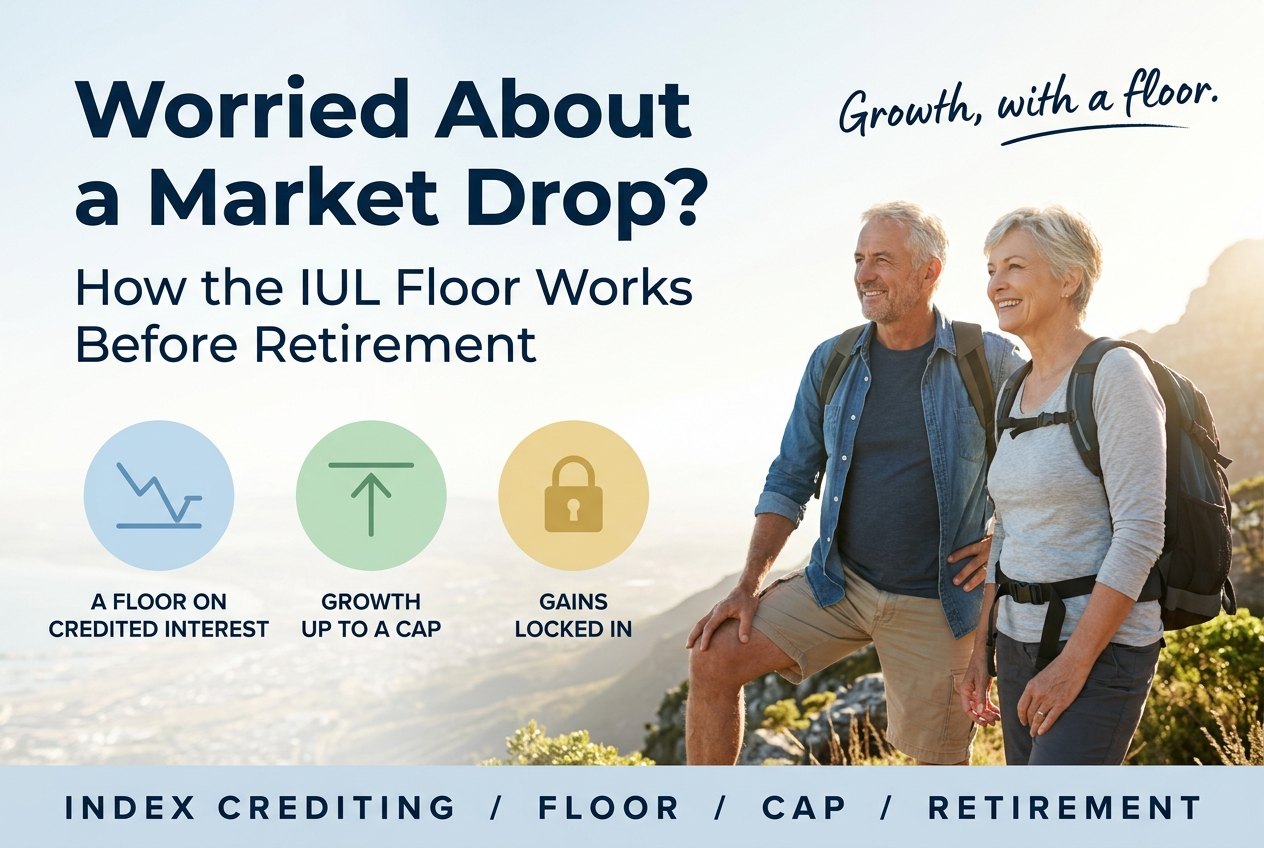
Couple in their late 50s hiking at a mountain overlook, under the title Worried About a Market Drop? How the IUL Floor Works Before Retirement

Indexed universal life (IUL) credits interest based on a market index, with a floor, usually 0%, so the interest credited in a bad year is never negative. In return, the upside is limited by a cap or participation rate. The floor protects credited interest, not the whole account: policy charges still come out every year.

Key takeaways

  • A market loss in the years just before or after retirement can do outsized damage because withdrawals lock it in.
  • IUL credits zero, not a loss, in a negative index year; gains are credited up to a cap or participation rate.
  • Policy charges still apply, so cash value can go down in a zero-credit year.
  • Caps and participation rates are not guaranteed and can change, within contract minimums.

Why a loss near retirement hurts more

Planners call it sequence-of-returns risk. If the market falls early in retirement while you are withdrawing money, you sell more shares to get the same income, and those shares are not there when the market recovers. The same average return can leave two retirees with very different outcomes depending on when the bad years land.

How IUL crediting works

Cash value is not invested in the market. The carrier credits interest based on how an index performs over a set period, usually one year, using three levers:

  • Floor: the lowest rate that can be credited, usually 0%.
  • Cap: the highest rate that can be credited for the period.
  • Participation rate: the share of the index gain that counts toward the credit.

A hypothetical example, for illustration only: with a 0% floor, a 10% cap and 100% participation, an index year of minus 15% credits 0%, an index year of plus 6% credits 6%, and an index year of plus 20% credits 10%. Credited interest is locked in each period, so a later down year does not take it back.

The floor does not make IUL an investment without risk. It means a bad market year costs you growth, not credited losses.

What the floor does not protect

  • Policy charges. Cost of insurance and other charges are deducted regardless of the index, so a zero-credit year can reduce cash value.
  • Changing caps. Carriers can lower caps and participation rates, subject to guaranteed minimums in the contract.
  • Illustrations. Projections assume a rate that may not happen. Ask to see a conservative scenario.

Where IUL fits in a retirement plan

IUL is best used as one bucket alongside retirement accounts, not instead of them. Some retirees draw from cash value in years when the market is down, which gives their investment accounts time to recover. Others use it for tax-free income to manage their tax bracket.

It works best when it is funded for years before retirement. Someone who needs the money within 10 to 15 years, or who cannot fund a policy consistently, is usually better served by other tools.

Frequently asked questions

Can my IUL lose value?

Yes. The floor applies to credited interest, not to the account. Policy charges are deducted every year, so cash value can decline in a year with little or no credited interest.

Are caps guaranteed?

No. Current caps and participation rates can change. The contract states the guaranteed minimums.

Is my money invested in the stock market?

No. The index is only used to calculate the interest credited. Your cash value is not invested in the index.

Is IUL better than an annuity for downside protection?

They solve different problems. A fixed indexed annuity is built for retirement income and has no death benefit or cost of insurance; IUL adds life insurance and tax-free access through loans.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Maxed Out Your 401(k)? How High Earners Use Indexed Universal Life

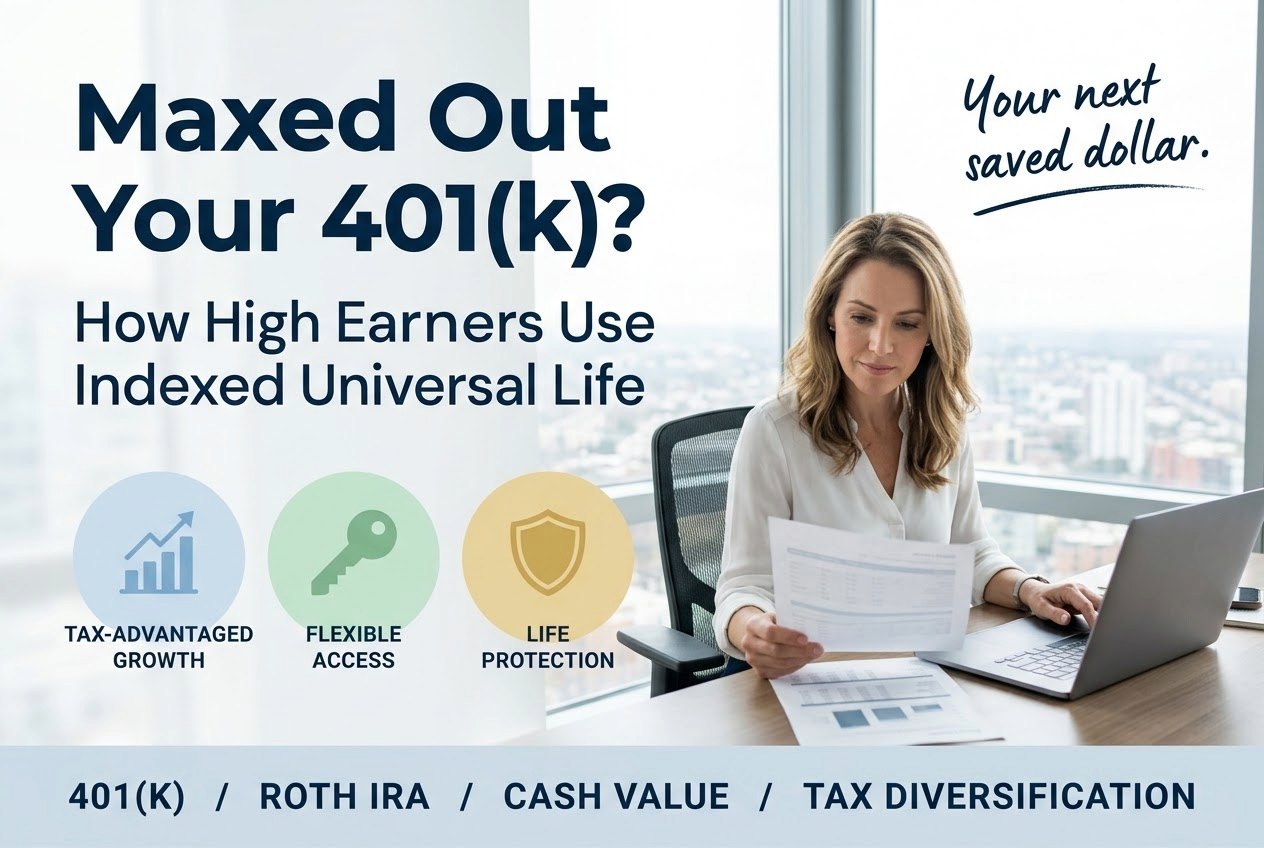
Professional woman reviewing documents at a desk with a city view, under the title Maxed Out Your 401(k)? How High Earners Use Indexed Universal Life

Once a high earner has maxed out their 401(k) and earns too much to contribute directly to a Roth IRA, a well-funded indexed universal life (IUL) policy is one more place to save with tax advantages. There are no IRS income limits on who can buy one, growth is tax-deferred, and money can be reached tax-free through policy loans when the policy is designed and kept in force correctly.

Key takeaways

  • In 2026 the 401(k) employee limit is $24,500, and direct Roth IRA contributions phase out between $153,000 and $168,000 (single) or $242,000 and $252,000 (married filing jointly).
  • IUL premiums are limited by life insurance tax rules (the MEC limits), not by your income.
  • Money comes out through withdrawals up to what you paid in, then policy loans.
  • It is life insurance first: there are policy costs, and it works best over 15 years or more.

The gap high earners run into

For 2026 the IRS lets employees defer $24,500 into a 401(k), 403(b) or most 457 plans, plus catch-up contributions if they are 50 or older. Direct Roth IRA contributions phase out between $153,000 and $168,000 of modified adjusted gross income for single filers and between $242,000 and $252,000 for married couples filing jointly.

Above those levels, the remaining options are a backdoor Roth IRA, a taxable brokerage account, a deferred compensation plan if the employer offers one, or cash value life insurance. Each has a place. IUL appeals to people who also need life insurance and want tax-free income later.

How IUL fills the gap

An IUL policy builds cash value that is credited interest based on a market index, with a floor that keeps credited interest from going below zero and a cap or participation rate on the upside. The cash value grows tax-deferred.

How much you can put in is set by the tax code’s life insurance rules (sections 7702 and 7702A), which tie premiums to the death benefit. There is no income test. A policy funded too quickly becomes a modified endowment contract (MEC), which makes loans and withdrawals taxable first, so accumulation designs are built to stay just under that line.

For many high earners the question is not whether to save more. It is where the next saved dollar will be taxed least.

How the money comes out

  • Withdrawals up to your basis (the premiums you paid) are generally not taxable.
  • Policy loans after that are generally not taxable while the policy stays in force and is not a MEC.
  • The death benefit passes to beneficiaries generally free of income tax.

The catch is that loans accrue interest and reduce the death benefit. If a policy lapses with a large loan outstanding, the gain can become taxable all at once. Income plans need to leave enough value in the policy to keep it in force for life.

What it costs, and who it is not for

IUL has cost of insurance, policy charges and surrender charges in the early years. A taxable brokerage account has no insurance costs, so IUL only makes sense when the tax benefits and the death benefit are worth those charges to you. It is usually not a fit for money you may need within 10 to 15 years, for anyone who cannot fund it consistently, or for someone looking only for investment returns.

Designing it well

Accumulation IUL is usually designed with the smallest death benefit the tax rules allow for the planned premiums, an increasing death benefit option while you are funding it, and a switch to a level death benefit before income begins. Ask to see illustrations at more than one crediting rate, including a conservative one.

Frequently asked questions

Is IUL a replacement for a Roth IRA?

No. It is a complement. Many high earners do a backdoor Roth IRA first, then use IUL for additional savings, especially if they also need life insurance.

What is a MEC?

A modified endowment contract is a life insurance policy funded faster than the tax code allows. It loses tax-free access: loans and withdrawals are taxed as income first and may carry a 10% penalty before age 59½.

Are there income limits to buy IUL?

No. Premium limits come from the life insurance tax rules and the death benefit, not your income. Carriers do underwrite coverage amounts based on income and net worth.

How long should I plan to fund it?

Most accumulation designs assume funding for at least 7 to 10 years and holding the policy 15 years or more before taking income.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

Sources: IRS: 2026 401(k) and IRA limits

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Do Policy Loans Count Toward IRMAA or Social Security Taxes?

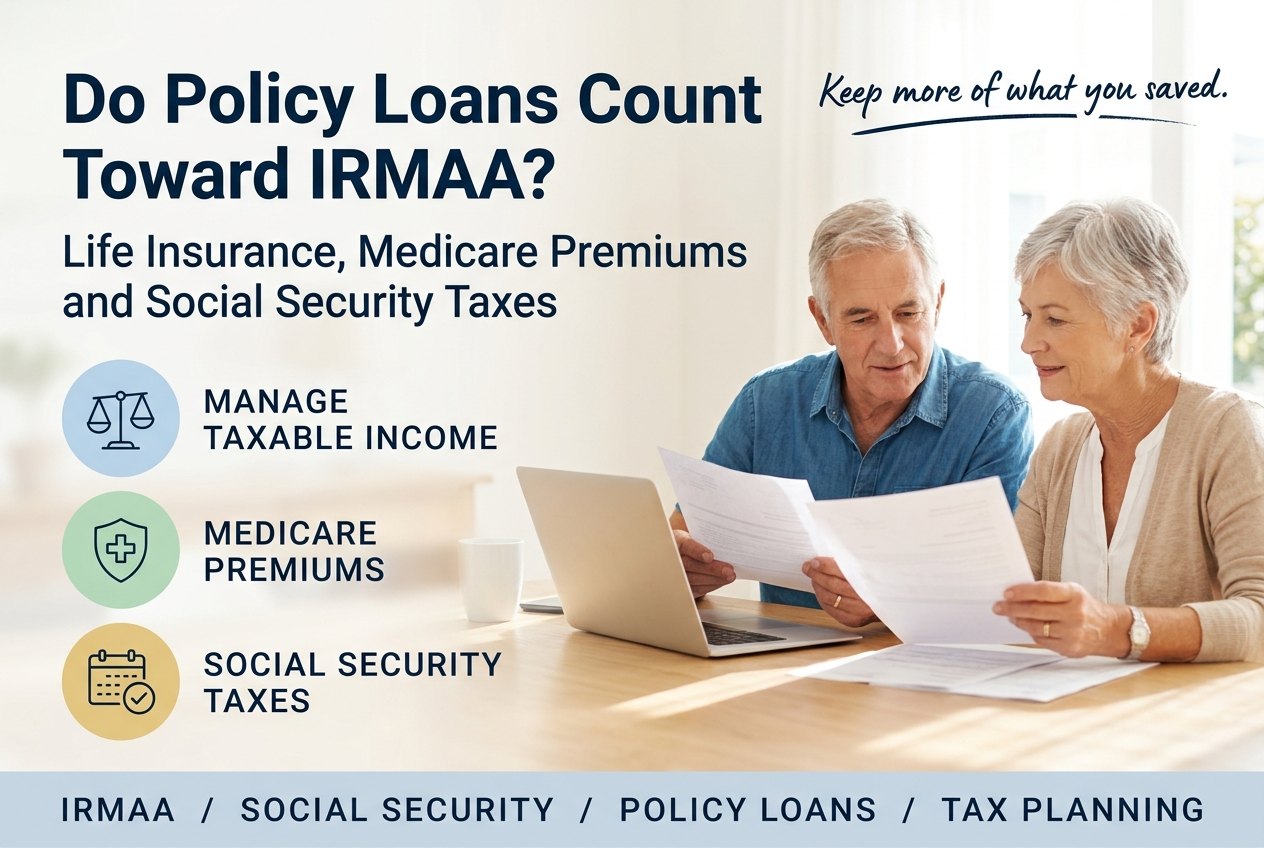
Retired couple reviewing paperwork and a laptop at a dining table, under the title Do Policy Loans Count Toward IRMAA?

Generally, no. Loans from a life insurance policy that is not a modified endowment contract and stays in force are not taxable income. That means they do not count in the modified adjusted gross income Medicare uses for IRMAA surcharges, or in the combined income that decides how much of your Social Security is taxed.

Key takeaways

  • For 2026, IRMAA surcharges on Medicare Part B and Part D begin above $109,000 of MAGI for individuals and $218,000 for joint filers.
  • Up to 85% of Social Security benefits can be taxed once combined income passes $34,000 (single) or $44,000 (joint).
  • Policy loans do not show up in either calculation; 401(k) and IRA withdrawals do.
  • The policy must stay in force: a lapse with a loan outstanding can create taxable income.

How IRMAA works

Medicare’s income-related monthly adjustment amount (IRMAA) adds a surcharge to Part B and Part D premiums for people with higher income. For 2026 the standard Part B premium is $202.90 a month, and surcharges start when modified adjusted gross income is above $109,000 for individuals or $218,000 for married couples filing jointly. Medicare uses your tax return from two years earlier, so 2024 income sets 2026 premiums.

Because the brackets are cliffs, one extra dollar of income can raise premiums for the whole year. A large IRA withdrawal, a Roth conversion or a capital gain can push someone over.

How Social Security is taxed

The IRS looks at your combined income: adjusted gross income, plus nontaxable interest, plus half of your Social Security benefits. For single filers, up to 50% of benefits can be taxed above $25,000 and up to 85% above $34,000. For joint filers, the levels are $32,000 and $44,000. These thresholds are not indexed for inflation, so more retirees cross them every year.

Every dollar of retirement income is taxed somewhere. The planning question is which bucket it comes from, and in which year.

Where policy loans fit

A policy loan is a loan against your cash value, not income, so it is not reported on your tax return. Used alongside retirement account withdrawals, it lets a retiree take the income they need while keeping reported income under an IRMAA bracket or a Social Security threshold.

  • Withdrawals up to your basis (premiums paid) are also generally not taxable.
  • Roth IRA qualified distributions are tax-free too; cash value is another source alongside them.
  • Traditional IRA and 401(k) withdrawals, pensions and most annuity income are taxable and count toward both calculations.

The catches

Policy loans accrue interest, and they reduce the death benefit. If a policy lapses or is surrendered with a loan outstanding, the gain above your basis becomes taxable in that year, which could cause the very IRMAA and tax problem you were avoiding. Income from a policy needs to be planned so the policy stays in force for life.

This also only works if the policy was funded years earlier. It is a strategy to set up in your 40s and 50s, not the year you retire.

Frequently asked questions

Are life insurance withdrawals taxable?

Withdrawals up to your basis, the premiums you paid, are generally not taxable. Amounts above basis are taxable unless taken as a policy loan.

Do I pay interest on a policy loan?

Yes. Policy loans accrue interest. Some policies offer fixed-rate loans and others variable or indexed loans, each with different risks.

Does this work with a MEC?

No. Loans and withdrawals from a modified endowment contract are taxed as income first, so they can count toward IRMAA and Social Security taxation.

Which year’s income sets IRMAA?

Medicare generally uses your tax return from two years earlier. For 2026 premiums, that is your 2024 return.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

Sources: CMS: 2026 Medicare Parts A & B premiums · SSA: income taxes on benefits

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Life Insurance vs. a 529 Plan: Saving for a Child Who May Not Go to College

Parent and teenage son talking at a kitchen table with a laptop, college brochures and a toolbox, under the title Life Insurance vs. a 529 Plan: Saving for a Child Who May Not Go to College

For most families, a 529 plan is the most efficient way to save for college. Cash value life insurance appeals to parents who want flexibility if their child chooses a trade, starts a business or skips college, and who also want the plan protected if a parent dies. Many families use both.

Key takeaways

  • 529 earnings are tax-free when spent on qualified education; earnings used for other purposes are taxed and usually hit with a 10% additional tax.
  • Cash value life insurance can be used for anything, through withdrawals and policy loans, with no education requirement.
  • Cash value is generally not reported as an asset on the FAFSA.
  • Life insurance needs years of consistent funding before the cash value is meaningful.

Where a 529 plan shines

A 529 plan is purpose-built for education. Growth is tax-deferred, withdrawals for qualified education expenses are tax-free, and many states give a state income tax deduction for contributions. Under SECURE 2.0, a 529 that has been open at least 15 years can also roll up to $35,000, over the beneficiary’s lifetime, into a Roth IRA for that beneficiary, subject to annual Roth limits.

The trade-off is the restriction. Earnings withdrawn for non-qualified expenses are subject to income tax and, in most cases, a 10% additional tax. That additional tax is waived up to the amount of a tax-free scholarship, but the income tax still applies.

Where cash value life insurance fits

A permanent policy, such as indexed universal life or whole life, builds cash value that can be reached through withdrawals and policy loans for any purpose. If your child becomes an electrician, a business owner or a missionary instead of a college student, the money is still usable without a penalty.

There are two common designs. A policy on a parent protects the plan: if the parent dies, the death benefit can fund the goal. A policy on the child builds a very long runway and gives the child lifelong coverage, and it is often started by grandparents.

The question is not which account is better. It is how sure you are that the money will be spent on college.

Side by side

529 planCash value life insurance
Best forMoney you are confident will pay for educationMoney that may be used for education or something else
Tax on growthTax-deferred; tax-free for qualified educationTax-deferred; tax-free access through loans and withdrawals to basis if designed and kept in force correctly
Non-education useEarnings taxed plus, usually, a 10% additional taxNo penalty; loans reduce the death benefit
FAFSAParent-owned 529 is reported as a parent assetGenerally not reported
Death benefitNoneYes
Early-year costsLowHigher; surrender charges in early years

The honest trade-offs

Life insurance has costs a 529 does not: cost of insurance, policy charges and surrender charges in the early years. That means cash value grows slowly at first and needs roughly 10 to 15 years or more to work well. If college is only a few years away, a 529 or a savings account is usually the better tool.

Loans and withdrawals also reduce the death benefit, and a policy that lapses with a loan outstanding can create a tax bill. The policy needs to be designed and monitored with the goal in mind.

Using both

Many families put their base college savings in a 529, then add a cash value policy for flexibility and protection. That way the education dollars get the best tax treatment, and the family still has money that can go anywhere life leads. See how SRS approaches college funding.

Frequently asked questions

Is cash value life insurance counted on the FAFSA?

Cash value life insurance is generally not reported as an asset on the FAFSA. Schools that use the CSS Profile may ask about it.

What happens to a 529 if my child gets a scholarship?

You can withdraw up to the scholarship amount without the 10% additional tax, but the earnings portion is still subject to income tax.

Can I use a 529 and life insurance together?

Yes. Many families use a 529 for money they are confident will go to education and cash value life insurance for flexibility and protection.

How long before the cash value is useful?

It depends on the design and funding, but cash value life insurance usually needs 10 to 15 years or more to build meaningful value.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

Sources: IRS Publication 970 (529 plans) · Saving for College: assets and financial aid

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Why Grandparents Buy Life Insurance for Their Grandchildren

Grandparents helping their young grandson plant a tree in the backyard, under the title Why Grandparents Buy Life Insurance for Their Grandchildren

Grandparents buy permanent life insurance on a grandchild to give a gift that keeps growing for decades: coverage the child keeps for life, plus cash value that can later help with college, a first home or a business. The grandparent owns and pays for the policy, so they stay in control until they decide to hand it over.

Key takeaways

  • The grandparent is usually the owner and payor; a parent or guardian normally signs the application for a minor.
  • Starting young means low insurance costs and many decades for cash value to grow.
  • The grandchild keeps coverage for life, no matter what happens to their health later.
  • Handing the policy to the grandchild later counts as a gift, so plan the timing with a tax advisor.

What grandparents are really buying

Most grandparents who ask about this are not worried about a death benefit on a child. They want to leave something meaningful that outlasts them, and they would rather not hand an 18-year-old a check. A permanent policy lets them do both: it builds value slowly and quietly, and it arrives with guardrails.

  • A head start. Cash value that can grow for 20, 30 or 50 years before anyone needs it.
  • Lifelong insurability. Coverage that stays in place even if the grandchild later develops diabetes, heart disease or another condition that makes insurance expensive or unavailable.
  • A legacy with a story. Many grandparents hand the policy over at a milestone, such as graduation, a wedding or age 30, along with a letter about why they started it.

How the policy is set up

Three roles matter. The owner controls the policy and pays the premiums; this is usually the grandparent. The insured is the grandchild. The beneficiary, who receives the death benefit, is often a parent while the child is young.

Name a successor owner too, usually a parent. If the grandparent dies before handing the policy over, the successor owner takes control and the policy keeps going instead of ending up in the grandparent’s estate paperwork.

When the grandchild is ready, ownership can be transferred to them. That transfer is a gift. In 2026 the IRS annual gift tax exclusion is $19,000 per recipient, and the value of a transferred policy is generally measured by its value at the time of transfer, not the premiums paid. A tax advisor can help time it.

The most valuable part of the gift may be insurability: coverage locked in before the grandchild has any health history at all.

Whole life or indexed universal life?

Whole life has guaranteed cash value growth and fixed premiums. It suits grandparents who want predictability and a set payment schedule.

Indexed universal life (IUL) credits interest based on a market index, with a floor that keeps credited interest from going below zero, and it allows flexible premiums. It suits grandparents who want more growth potential and are comfortable with non-guaranteed crediting. Policy charges apply to both designs, so either one needs to be funded as planned.

What the money can do later

Once the grandchild owns the policy, they can use the cash value through withdrawals and policy loans for anything: tuition, a down payment, starting a business, or leaving it alone to keep growing. Unlike a 529 plan, there is no penalty if the money is not spent on education.

Cash value life insurance is also generally not reported as an asset on the FAFSA. Some private colleges that use the CSS Profile ask about it, so check with the schools on the list.

Limits and things to watch

  • Coverage limits. Carriers cap how much insurance a child can have, often based on how much coverage the parents carry.
  • Early years. Surrender charges and policy costs are highest in the first 10 to 15 years, so this works best as a long-term gift.
  • Funding. Paying in too much too fast can turn the policy into a modified endowment contract (MEC), which changes how withdrawals and loans are taxed. The policy should be designed to stay under those limits.
  • Consent. Rules on who can insure a child vary by state and carrier.

Frequently asked questions

Do the parents need to agree?

Usually yes. Most carriers require a parent or legal guardian to sign the application for a minor, and rules vary by state.

Can I buy a policy for each grandchild?

Yes. Each grandchild gets a separate policy, and each one is subject to the carrier’s coverage limits for children.

What happens if I die before I hand the policy over?

If you name a successor owner, usually a parent, that person takes over ownership and the policy continues.

Does the cash value count against financial aid?

Cash value life insurance is generally not reported as an asset on the FAFSA. Some schools that use the CSS Profile may ask about it.

Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.

Sources: IRS: gift tax FAQs · Saving for College: assets and financial aid

General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-30

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.
