Once a high earner has maxed out their 401(k) and earns too much to contribute directly to a Roth IRA, a well-funded indexed universal life (IUL) policy is one more place to save with tax advantages. There are no IRS income limits on who can buy one, growth is tax-deferred, and money can be reached tax-free through policy loans when the policy is designed and kept in force correctly.
Key takeaways
- In 2026 the 401(k) employee limit is $24,500, and direct Roth IRA contributions phase out between $153,000 and $168,000 (single) or $242,000 and $252,000 (married filing jointly).
- IUL premiums are limited by life insurance tax rules (the MEC limits), not by your income.
- Money comes out through withdrawals up to what you paid in, then policy loans.
- It is life insurance first: there are policy costs, and it works best over 15 years or more.
The gap high earners run into
For 2026 the IRS lets employees defer $24,500 into a 401(k), 403(b) or most 457 plans, plus catch-up contributions if they are 50 or older. Direct Roth IRA contributions phase out between $153,000 and $168,000 of modified adjusted gross income for single filers and between $242,000 and $252,000 for married couples filing jointly.
Above those levels, the remaining options are a backdoor Roth IRA, a taxable brokerage account, a deferred compensation plan if the employer offers one, or cash value life insurance. Each has a place. IUL appeals to people who also need life insurance and want tax-free income later.
How IUL fills the gap
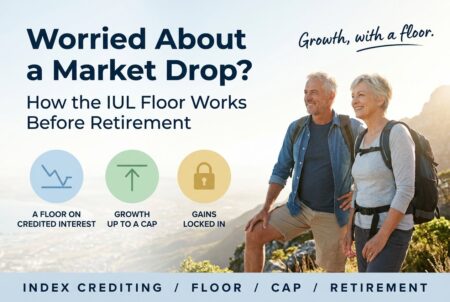
An IUL policy builds cash value that is credited interest based on a market index, with a floor that keeps credited interest from going below zero and a cap or participation rate on the upside. The cash value grows tax-deferred.
How much you can put in is set by the tax code’s life insurance rules (sections 7702 and 7702A), which tie premiums to the death benefit. There is no income test. A policy funded too quickly becomes a modified endowment contract (MEC), which makes loans and withdrawals taxable first, so accumulation designs are built to stay just under that line.
For many high earners the question is not whether to save more. It is where the next saved dollar will be taxed least.
How the money comes out
- Withdrawals up to your basis (the premiums you paid) are generally not taxable.
- Policy loans after that are generally not taxable while the policy stays in force and is not a MEC.
- The death benefit passes to beneficiaries generally free of income tax.
The catch is that loans accrue interest and reduce the death benefit. If a policy lapses with a large loan outstanding, the gain can become taxable all at once. Income plans need to leave enough value in the policy to keep it in force for life.
What it costs, and who it is not for
IUL has cost of insurance, policy charges and surrender charges in the early years. A taxable brokerage account has no insurance costs, so IUL only makes sense when the tax benefits and the death benefit are worth those charges to you. It is usually not a fit for money you may need within 10 to 15 years, for anyone who cannot fund it consistently, or for someone looking only for investment returns.
Designing it well
Accumulation IUL is usually designed with the smallest death benefit the tax rules allow for the planned premiums, an increasing death benefit option while you are funding it, and a switch to a level death benefit before income begins. Ask to see illustrations at more than one crediting rate, including a conservative one.
Frequently asked questions
Is IUL a replacement for a Roth IRA?
No. It is a complement. Many high earners do a backdoor Roth IRA first, then use IUL for additional savings, especially if they also need life insurance.
What is a MEC?
A modified endowment contract is a life insurance policy funded faster than the tax code allows. It loses tax-free access: loans and withdrawals are taxed as income first and may carry a 10% penalty before age 59½.
Are there income limits to buy IUL?
No. Premium limits come from the life insurance tax rules and the death benefit, not your income. Carriers do underwrite coverage amounts based on income and net worth.
How long should I plan to fund it?
Most accumulation designs assume funding for at least 7 to 10 years and holding the policy 15 years or more before taking income.
Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.
Sources: IRS: 2026 401(k) and IRA limits
General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.
Reviewed by Tim Fuller on 2026-09-30
Tim Fuller
President, SRS Inc.
Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.
Connect on LinkedIn →We’re Here to Help
Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.