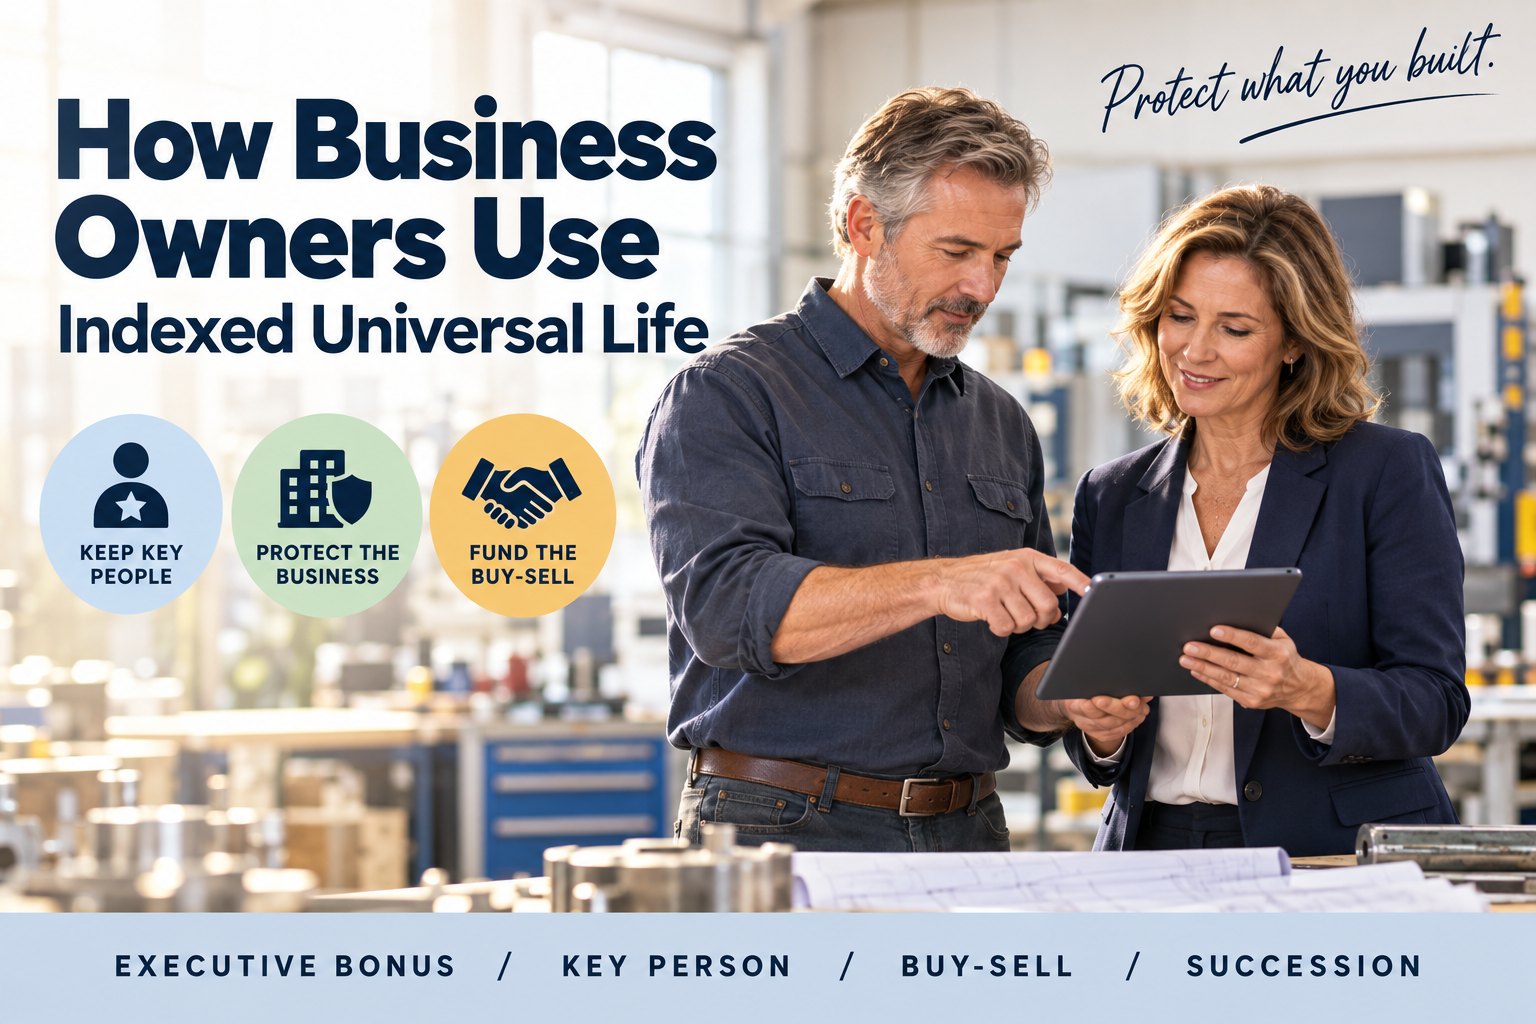
Business owners use indexed universal life (IUL) for three main jobs: rewarding and keeping key employees through executive bonus plans, protecting the business if a key person dies, and funding buy-sell agreements. The cash value can also become supplemental retirement money for the owner or the employee later.
Key takeaways
- Executive bonus (Section 162): the business pays the premium as a bonus, generally deductible as compensation, and the employee owns the policy.
- Key person: the business owns the policy and receives the death benefit; premiums are not deductible.
- Buy-sell: life insurance funds the purchase of an owner’s share at death, and cash value can help with a lifetime buyout.
- Employer-owned policies need notice and written consent before they are issued.
Executive bonus plans (Section 162)
The business pays the premium on a policy owned by the employee and reports it as a bonus. The bonus is generally deductible to the business as reasonable compensation and taxable income to the employee; some plans add a bonus to cover that tax. The employee gets a death benefit for their family and cash value they can use later.
A restricted executive bonus adds a vesting schedule or other restrictions, so the employee has a reason to stay. It is a simple way to create “golden handcuffs” without a qualified plan.
Key person protection
If a top salesperson, engineer or co-owner dies, the business can lose revenue, credit and time. With key person coverage, the business owns the policy, pays the premium and receives the death benefit to recruit a replacement, reassure lenders and keep operating. Premiums are not deductible, and the cash value is a business asset.
Employer-owned life insurance must meet the notice and consent rules in IRC section 101(j) before the policy is issued, or part of the death benefit can become taxable. Your advisor and CPA should confirm the paperwork is in place.
For many business owners, the business is the biggest asset. Life insurance is often what makes the succession plan actually work.
Funding buy-sell agreements
A buy-sell agreement sets who buys an owner’s share, and at what price, if the owner dies, becomes disabled or leaves. Life insurance provides the money at death. In a cross-purchase plan the owners insure each other; in an entity purchase plan the business insures each owner. Cash value in an IUL can also help fund a buyout at retirement.
Retirement money for the owner
Owners who have maxed out their qualified plan sometimes use IUL as supplemental retirement savings, taking tax-free policy loans in retirement when the policy is designed and kept in force correctly. It pairs well with a business that has uneven cash flow, since IUL premiums can be flexible within limits.
See SRS business planning for key person, buy-sell, executive compensation and succession resources.
Frequently asked questions
Are life insurance premiums tax-deductible for a business?
Executive bonus premiums are generally deductible as compensation. Premiums on policies the business owns and benefits from, such as key person coverage, are not deductible.
What is a restricted executive bonus arrangement?
An executive bonus plan with a vesting schedule or other restrictions on the policy, used to encourage a key employee to stay.
Cross-purchase or entity purchase?
It depends on the number of owners, the business structure and tax goals. Work through it with your CPA and attorney.
Do employees have to consent to employer-owned life insurance?
Yes. Under IRC section 101(j), the employee must receive notice and give written consent before the policy is issued.
Financial professionals: download our free one-pager, Why Clients Buy Accumulation IUL, or request an illustration. Individuals: see who buys cash value life insurance, and who it’s not for, or ask Tim a question below.
General information, not tax, legal or investment advice. Tax treatment depends on proper policy design, keeping the policy in force and current law. Policy features, riders and availability vary by carrier and state. Illustrations are not guarantees.
Reviewed by Tim Fuller on 2026-09-30

Tim Fuller
President, SRS Inc.
Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.
Connect on LinkedIn →We’re Here to Help
Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.