
Call 303-309-3471 Advisors: get contracted with SRS →Get a Quote

Life Insurance With Type 2 Diabetes on Oral Medication: How Credits Improve the Offer

Active older man hiking a mountain trail, representing impaired risk life insurance clients living fully

Type 2 diabetes treated with diet and oral medication, such as metformin, is one of the most common impairments on life applications. Combined with a heavier build, it often starts as a table rating. With the right carrier, credits can bring that down significantly.

Key takeaways

  • Type 2 diabetes with diet and oral medication only, good control, and no complications may reach Standard Plus at some carriers for clients 50 and older.
  • Build combined with diabetes usually worsens the rating, but credits can offset it.
  • A 54-year-old woman with Type 2 diabetes and a heavier build went from Table 4 to Table 2 with credits.

Initial workup: Table 4. After credits for non-smoking, driving record, cardiac testing and blood pressure: Table 2.

What helps a Type 2 case

  • Treatment with diet and oral medication only, rather than insulin
  • Stable, good A1C readings over time
  • No complications such as kidney, eye, nerve, or heart disease
  • Controlled blood pressure and cholesterol
  • Diagnosis at an older age

Some carriers may offer Standard Plus to clients 50 and older with excellent control, diet and oral medication only, and no complications.

Case study: credits make the difference

  • 54-year-old female, non-tobacco, applying for $1 million of term
  • Type 2 diabetes treated with metformin
  • 5’3”, 220 lbs
  • Initial workup: Table 4

One A+ carrier applied credits for being a lifetime non-smoker, income over $100,000, a preferred-or-better driving record, negative cardiac testing, and controlled blood pressure. Final offer: Table 2.

Shop carriers with credit programs

Not every carrier applies lifestyle and health credits. Knowing which ones do can save your client meaningful premium. See underwriting upgrade programs and how A1C affects ratings.

Frequently asked questions

Can you get life insurance with Type 2 diabetes?

Yes. Many Type 2 diabetics qualify for Standard or better with good control and no complications, depending on the carrier.

Does taking metformin affect life insurance rates?

Metformin itself isn’t the issue; underwriters look at diabetic control, complications, and other risk factors.

What are underwriting credits?

Positive factors, such as non-smoking, good driving record, or favorable cardiac tests, that some carriers use to improve a rating.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-25

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.


Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Help Clients Hedge Long-Term Care Risk: Start With the Cost of Care

Adult daughter and her aging mother sharing a warm moment while discussing long-term care planning

Talking about the cost of care is one of the least threatening ways to start a long-term care discussion. It turns an uncomfortable topic into a numbers conversation, and it gives you the starting point for designing coverage.

Key takeaways

  • Start by asking where the client would want to receive care, then show today’s and future costs for that setting.
  • Coverage doesn’t have to insure the entire risk; clients can self-fund part of it.
  • Shorter benefit periods or a higher starting benefit without compound inflation can cut premiums significantly.

Long-term care coverage isn’t all-or-nothing. Clients can insure the part of the risk they can’t afford to carry themselves.

Highlight the cost of care

Ask where the client would want to receive care: at home, in assisted living, or in a facility. Then show what one to three years or more of that care costs today and what it could cost when they’re likely to need it. We can provide current costs by location and inflation-adjusted projections. National figures are in our 2025 cost of care summary.

Develop a strategy

Once clients see the impact on their assets, help them decide how much risk to insure. Some prefer to cover part of future costs and self-fund the rest. Others want full protection for a spouse or to preserve a legacy. Both are valid plans.

Manage the premium

  • Start with a design that covers the full projected cost, then show alternatives.
  • Shorten the benefit period to three to five years, which covers most care needs.
  • Consider a higher initial daily benefit with less inflation protection; dropping compound inflation can cut the premium substantially.

More options in five ways to make LTC more affordable.

Become the cost-of-care resource

Advisors who know local care costs become a go-to resource in their community. Use us as your reference point for data and illustrations.

Frequently asked questions

How much long-term care coverage does a client need?

Enough to cover the portion of expected care costs they can’t comfortably pay from income and savings. Many choose to insure part of the risk.

How long does a typical long-term care need last?

It varies widely. Many needs last a few years, which is why three- to five-year benefit periods are common.

Does leaving off inflation protection lower LTC premiums?

Yes, often substantially. A higher starting benefit can partly offset future cost increases.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-25

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

What Business Overhead Expense Insurance Covers, and What It Doesn’t

Professional working confidently at her desk, representing disability income protection

Most small business owners couldn’t step away for a long weekend, let alone several months. If illness or injury kept them out, the business could close. Business overhead expense (BOE) coverage is designed to keep it open, but owners should understand exactly what it pays for.

Key takeaways

  • BOE reimburses the business’s regular fixed operating expenses while the owner is disabled.
  • It generally doesn’t cover the owner’s own salary, inventory, or new equipment purchases.
  • Pair BOE with personal disability insurance so both the business and the owner’s income are protected.

BOE keeps the business alive. Personal disability insurance keeps the owner’s household running. Most owners need both.

What BOE typically covers

  • Rent or mortgage interest on business property
  • Utilities, phone, and internet
  • Salaries of employees (other than the insured, and often other same-profession employees)
  • Equipment leases and loan payments (with some policies or riders)
  • Business insurance premiums, accounting and professional fees, and other regular fixed expenses

What BOE typically doesn’t cover

  • The owner’s own salary or draw, which is covered by personal disability insurance
  • Inventory, merchandise, or cost of goods
  • Purchases of new equipment
  • Salaries of replacement professionals, unless a special rider is added; see the salary replacement rider for physicians and dentists

Definitions vary by carrier, so review each policy’s covered expenses list.

Why it’s a door opener

Asking “What would happen to your business if you couldn’t work for several months?” opens a conversation most owners have never had. It protects employees, keeps the business valuable enough to sell if the owner can’t return, and premiums are generally tax-deductible. See why small businesses need BOE.

Frequently asked questions

Does business overhead expense insurance cover the owner’s salary?

No. BOE covers business expenses; the owner’s income is protected by personal disability insurance.

Does BOE cover employee salaries?

Yes, generally for employees other than the insured, though same-profession employees may be excluded unless a rider is added.

Are BOE benefits taxable?

Premiums are generally deductible, and benefits are taxable income to the business but offset by the deductible expenses they pay.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-25

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Using RMDs to Fund Survivorship Life Insurance

Advisor and client reviewing an advanced markets estate planning strategy in a private office

Many retired couples take required minimum distributions they don’t need to live on. Redirecting those after-tax dollars into a survivorship life policy can turn a taxable distribution into a larger, income-tax-free inheritance. Getting the case approved, though, takes careful preparation.

Key takeaways

  • RMDs generally begin at age 73; unneeded distributions can be repositioned into second-to-die coverage.
  • Survivorship life pays at the second death, when heirs face the SECURE Act 10-year rule and possible estate or state taxes.
  • Underwriters need a real purpose — estate liquidity, equalization or asset distribution — not just “increase the legacy.”

“To increase the legacy” is not a purpose underwriters accept. Estate liquidity, inheritance equalization and ease of distribution are.

Why RMDs and survivorship life fit together

RMDs generally begin at age 73. Clients with enough other income often reinvest these distributions or leave them in a taxable account. When the IRA eventually passes to children, most non-spouse heirs must empty it within 10 years under the SECURE Act, often during their own peak earning years. Using the after-tax RMD to pay premiums on a survivorship (second-to-die) policy creates an income-tax-free death benefit at the second death, which can offset those taxes or simply leave heirs more. See IRA planning under the SECURE Act.

The underwriting challenge

Many middle-market retirees don’t have traditional financial justification. With a federal estate tax exemption of $15 million per person ($30 million per couple) from 2026, most won’t owe federal estate tax, and retirees have little earned income to replace. Carrier marketing sometimes promotes RMD strategies, but underwriters decide what gets issued.

Percent-of-net-worth justification

Many carriers are open to coverage for estate liquidity, inheritance equalization or making assets easier to divide. Some will allow coverage as a percentage of the client’s net worth, even without traditional need. The percentage varies by carrier, and existing coverage counts against it. State estate or inheritance taxes, which can apply at much lower levels than the federal tax, can also support a stated purpose.

How we help you place the case

Don’t just submit an application and hope. Share the client’s situation with us and we’ll informally shop it with receptive carriers. When you submit, we can write a cover letter that explains the purpose clearly. It’s worth the effort: a permanent policy on an older couple is a meaningful case for the client and for you. See also RMDs in life insurance sales.

Frequently asked questions

Can I use my RMD to pay for life insurance?

Yes. Once the RMD is withdrawn and taxes are paid, the remaining money can be used for any purpose, including premiums on a life insurance policy such as survivorship life.

Why use survivorship life for an RMD strategy?

Survivorship life insures two people and pays at the second death, which is when an inheritance passes to children. It usually costs less than two individual policies.

How do underwriters justify coverage for retirees?

Many carriers allow coverage based on a percentage of net worth for estate liquidity, equalization or ease of distribution. The stated purpose matters, so a clear cover letter helps.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-26

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Term Life Insurance for Business Loans and Debt

Happy family of four laughing together on the couch, representing life insurance protection

When a business owner borrows money, the lender is betting on that owner staying alive and able to run the company. Term life insurance is the most cost-effective way to protect the loan, the business and the owner’s family. Here’s how to structure it.

Key takeaways

  • Lenders, including many SBA lenders, often require life insurance on key owners, usually with a collateral assignment.
  • Match the term length and amount to the loan balance and schedule, and consider extra coverage for the family.
  • Term policies with living benefits can also help if the owner has a major illness while the loan is outstanding.

A collateral assignment pays the lender first — and the rest goes to the owner’s beneficiaries.

Why lenders ask for life insurance

If the owner dies, the business may struggle to repay. Lenders often require coverage on the owner or key people as a loan condition. The policy is typically owned by the borrower and assigned to the lender through a collateral assignment, so the lender is paid first and any remaining proceeds go to the beneficiaries. Confirm the lender’s specific requirements before applying.

Sizing and structuring the coverage

  • Amount: at least the loan balance, and often more so the family or business has money left after the lender is paid.
  • Term length: match or exceed the loan term. A 10-year loan pairs naturally with 10- or 15-year term.
  • Ownership: personal ownership with a collateral assignment is common; business ownership may also work depending on the structure.
  • Conversion: choose a policy with a strong conversion privilege in case the need becomes permanent.

Debt can also support additional key person coverage when losing the executive would affect repayment.

Living benefits add another layer

A heart attack, stroke or cancer diagnosis can hurt a business as badly as a death. Some term products include critical and chronic illness benefits that pay part of the death benefit while the insured is living. For a borrowing owner, that money can help keep payments current during recovery. Availability varies by carrier and state.

A natural door-opener

Business loans create a clear, immediate need, and the conversation often leads to broader planning: buy-sell funding, key person coverage and succession. See our business insurance needs checklist. Contact us and we’ll help you find competitive term options that meet lender requirements.

Frequently asked questions

Do banks require life insurance for business loans?

Many do, especially for SBA loans and loans that rely heavily on one owner. Requirements vary by lender and loan size.

What is a collateral assignment?

It is an agreement that gives the lender the right to be paid from the death benefit up to the outstanding loan balance. Remaining proceeds go to the policy’s beneficiaries.

How long should the term be?

At least as long as the loan. Many advisors choose a slightly longer term or a policy with a good conversion option in case the loan is extended or the need continues.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-26

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Lifestyle and Fitness Credits: A Three-Class Upgrade for an Active Diabetic Client

Underwriter reviewing medical and financial data with a client during risk assessment

Research consistently shows that fit people who live healthy lifestyles tend to live longer, even with minor health issues. One carrier puts that into practice by scoring lifestyle factors and using the score to improve ratings on permanent cases.

Key takeaways

  • The carrier scores lifestyle factors and medical tests from records for applicants through age 70.
  • The score can improve the underwriting class or offset a table rating on permanent products.
  • A 64-year-old business owner with Type 2 diabetes moved from Table 2 to Standard Plus Non-Nicotine: a three-class upgrade.

Initial offer: Table 2. After credits for exercise, no nicotine, and normal screenings: Standard Plus Non-Nicotine.

How the credits work

During underwriting, the carrier reviews medical records for specific lifestyle factors and test results, scores each one, and uses the total to improve the class or offset a table rating.

Case study

  • 64-year-old male business owner, 5’11”, 195 lbs
  • Applying for $1.2 million of universal life
  • Non-insulin-dependent (Type 2) diabetes, with good A1C control over five years
  • Initial offer: Table 2

Credits applied for: never using nicotine, regular aerobic exercise four times a week documented in his physician’s records, a normal colonoscopy, and normal PSA testing. Final offer: Standard Plus Non-Nicotine.

Why documentation matters

Credits depend on what’s in the medical records. Encourage clients to discuss exercise and keep screenings current with their doctors, so the evidence is there. See documenting health improvements and diabetes underwriting.

Frequently asked questions

Does exercise help with life insurance rates?

At some carriers, documented regular exercise can earn credits that improve the rating.

Can credits offset a table rating?

Yes. Some carriers use lifestyle credits to reduce or remove table ratings on permanent products.

What lifestyle factors earn life insurance credits?

Examples include no nicotine use, regular exercise documented by a physician, and normal cancer screenings.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-25

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Selling Long-Term Care With Storytelling: Why Stories Beat Statistics

Adult daughter and her aging mother sharing a warm moment while discussing long-term care planning

You already know statistics don’t sell long-term care insurance. Most people don’t see themselves in the numbers, and listing product features doesn’t help if they don’t believe they’ll need care. Stories do what data can’t.

Key takeaways

  • Clients connect with stories about real people, not probabilities or product features.
  • Good stories are relevant to the client, focus on feelings, and end well because of the coverage.
  • In one survey of LTC policyholders, 78% had a family member or friend who needed long-term care, so most clients have a story of their own.

78% of long-term care policyholders in one survey had a family member or friend who needed care. Your client probably has a story too.

Find a good story

You likely already have one. If you’ve cared for a parent or grandparent, you know how hard it is. Stories can also come from family, friends, or clients (with their permission and details changed). See one example in how an LTC policy helped Joe stay at home.

Make it memorable

  • Paint a picture. Don’t just describe events; describe how people felt.
  • Keep it relevant. A client with no children won’t connect with a story about the burden on adult kids.
  • End well. Don’t scare people. The story should have a better outcome because coverage was in place.

Invite the client’s story

Your story often prompts clients to recall their own. Five questions to draw it out:

  1. Do you know someone who needed long-term care?
  2. Who provided their care?
  3. What effect did that have on the caregiver and the family?
  4. How did they pay for it?
  5. What did it do to their finances, retirement plans, or the inheritance they hoped to leave?

Frequently asked questions

Why don’t statistics sell long-term care insurance?

Most people believe the risk applies to someone else. Personal stories make the need real in a way numbers don’t.

What makes a good long-term care sales story?

It’s relevant to the client, focuses on emotions and real outcomes, and ends positively because coverage was in place.

How do I get clients to share their own care experiences?

Ask whether they know someone who needed care, who provided it, and how it affected the family’s finances.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-25

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Why Disability Income Insurance Is the Foundation of a Financial Plan

Professional working confidently at her desk, representing disability income protection

Ask clients to name their most valuable asset and most say their home or retirement account. In reality, it’s their ability to earn an income, because every other part of their financial plan depends on it.

Key takeaways

  • Income funds every other goal: savings, insurance, investments, and lifestyle.
  • In a Council for Disability Awareness study, 71% of consumers thought disabilities were mostly caused by serious accidents; in reality only about 9% of long-term claims are.
  • Most people rate their ability to earn as their most important financial resource, yet only about a third have taken steps to protect it.

About 91% of long-term disability claims come from illnesses and common conditions, not serious accidents.

Income is the asset behind every other asset

Without income, no savings, investment, or insurance plan can be funded. Yet disability income is one of the most overlooked parts of financial planning, often because clients and advisors misunderstand the risk.

The misconception that drives the gap

In a Council for Disability Awareness consumer study, 71% of respondents believed disabilities are mostly caused by serious accidents. Insurance data shows only about 9% of long-term disability claims result from accidents. The rest come from back and joint problems, chronic diseases, cancer, mental health conditions, and pregnancy. More in four misconceptions about disability.

The protection gap

Nearly everyone in the same study rated their ability to earn as more important to their financial security than any other resource, but only 37% had thought about protecting it.

How we help

We work with leading disability carriers to find coverage for clients in almost any occupation, from simplified issue to fully underwritten, with the goal of getting clients protected quickly.

Frequently asked questions

What causes most long-term disabilities?

Illnesses and chronic conditions, such as back and joint disorders, cancer, heart disease, and mental health conditions, not accidents.

Why is disability insurance important?

Income pays for everything else in a financial plan. Disability insurance replaces part of it if illness or injury prevents working.

What is a person’s most valuable financial asset?

For most working people, their ability to earn an income over their career.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-25

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

The 10-Minute Life Insurance Needs Analysis

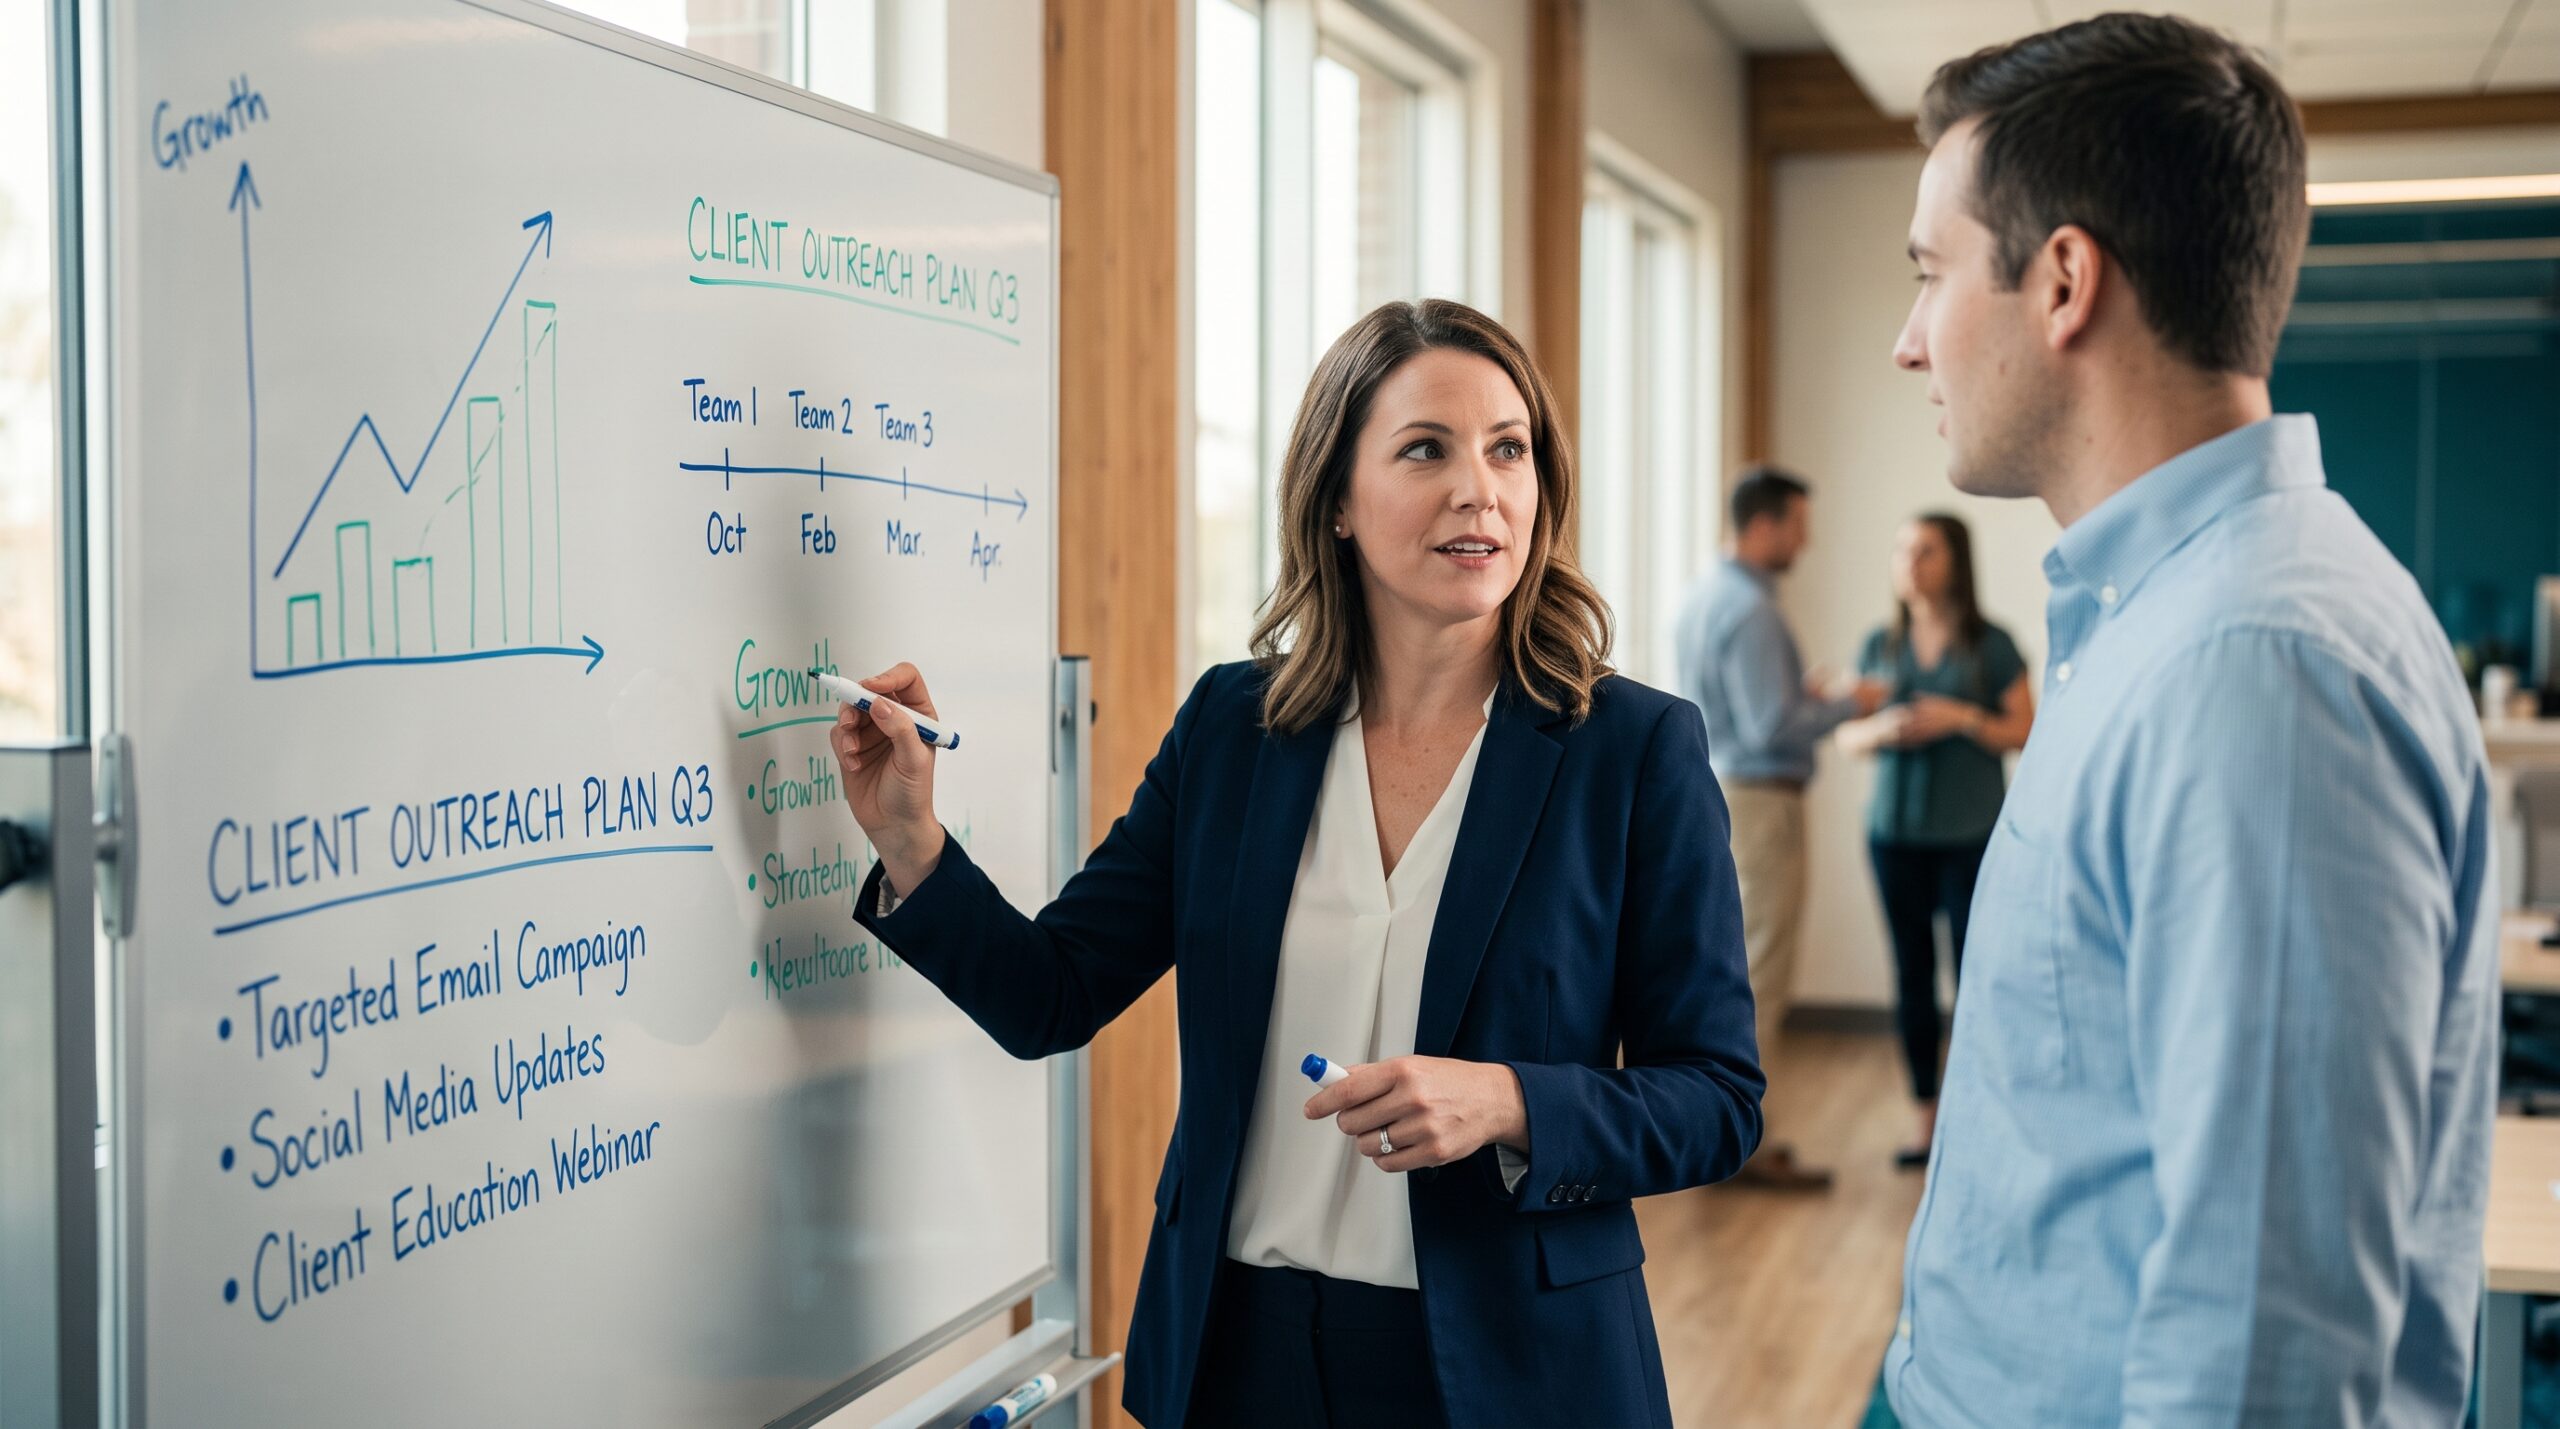
Advisor presenting a client outreach marketing plan on a whiteboard to a colleague

Clients today expect speed. Carriers have responded with accelerated underwriting, and advisors can do the same with the needs analysis. For most families, a simple income-based calculation gets you to the right amount of coverage in about ten minutes.

Key takeaways

  • For clients without estate tax concerns, the main life insurance need is usually income replacement.
  • A quick estimate: current earned income times remaining working years, with after-tax income as a lower bound.
  • Level term matched to the working years is typically the most economical fit, with conversion for later needs.

If a client has no estate tax concern, their only real life insurance need is usually income replacement.

For most people, there is one need

With a federal estate tax exemption of $15 million per person from 2026, most families don’t face federal estate tax. For them, the core need is replacing income. If the household is on track, keeping that income coming for the remaining working years lets the family maintain its lifestyle and still reach retirement goals.

A simple calculation

Multiply the client’s current earned income by the number of working years left. Because the death benefit is income-tax-free, using after-tax income can justify a somewhat lower amount. Carriers use income multiples by age for financial underwriting, so check your figure against carrier income multiples.

Term fits the need

The need lasts a known period: the working years. That’s exactly what level term covers. Clients can lock in a guaranteed cost for that period. As working years decline, the face amount can be reduced, though many clients keep it level to account for raises, bonuses and inflation. For needs after retirement, such as estate liquidity, clients can buy permanent coverage or use the term policy’s conversion privilege.

Don’t forget the spouse

Propose two policies. A working spouse needs income replacement too. A stay-at-home spouse also needs coverage large enough to pay for the childcare and household services they provide. A streamlined process like this also makes smaller term cases more worthwhile for you. Contact us for quotes or help with any case.

Frequently asked questions

How do you quickly estimate life insurance needs?

Multiply the client’s annual earned income by the number of working years remaining. Using after-tax income gives a reasonable lower bound because death benefits are generally income-tax-free.

Should a stay-at-home spouse have life insurance?

Yes. The coverage should be enough to pay for childcare and household services the spouse provides, so the family can keep its routine.

When is permanent insurance needed instead of term?

Permanent coverage fits needs that last for life, such as estate liquidity, business succession or leaving a legacy. Term with a conversion option can bridge to those needs later.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-26

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Who Are Your Best Business Owner Prospects for Life Insurance?

Advisor and client reviewing an advanced markets estate planning strategy in a private office

Business owners who ask what their company is worth are often really asking bigger questions: how to exit, how to protect the business, and how to pass it on. Those conversations lead naturally to life insurance. Here is a practical profile of the owners most likely to need your help.

Key takeaways

  • Owners who request a business valuation are usually signaling exit, succession or protection needs that life insurance can solve.
  • Closely held companies in professional services, manufacturing, construction, wholesale and retail trade are frequent valuation seekers.
  • Buy-sell funding, key person coverage and executive bonus plans are the three most common planning outcomes.

A business valuation is rarely the end goal. It is the opening to a conversation about exit planning, protection and the next generation.

Why business valuations signal a planning need

An owner who wants to know what the business is worth is usually thinking about what happens next: selling, retiring, bringing in a partner, or handing the company to family. Each of those events creates a funding question, and life insurance is often the most efficient answer.

Planning needs that commonly surface include exit and succession planning, business continuation and protection, wealth transfer to the next generation, and supplemental retirement income for the owner.

The profile of a strong business owner prospect

Industries that commonly seek business valuations include:

  • Professional, scientific and technical services
  • Manufacturing
  • Construction
  • Wholesale trade
  • Retail trade

These are typically closely held S or C corporations, with some partnerships, employing fewer than 100 people and often operating for decades. Many have annual revenue in the low millions, which is large enough to create real value to protect but small enough that the business depends heavily on one or two owners.

The three planning solutions that follow

  • Buy-sell funding. Life insurance gives surviving owners or the company the cash to buy a deceased owner’s interest at a fair price. See our overview of cross-purchase buy-sell planning.
  • Key person coverage. Protects the business against the loss of an owner or employee whose skills drive revenue.
  • Executive bonus plans. A simple way to reward and retain key people with employer-funded permanent coverage.

Family businesses and the next generation

Most family businesses do not survive into the second generation, and far fewer reach the third. Life insurance on the owners can provide the liquidity the next generation needs to keep the business running, pay estate costs, or buy out family members who are not involved.

It is also a clean way to equalize inheritances. If one child will run the business and another will not, a policy can leave the non-active child an equal share without splitting ownership and creating tension.

Frequently asked questions

Why are business valuation requests a good lead for life insurance?

Owners who want a valuation are usually preparing for a sale, succession or partner change. Each of those events needs funding, and life insurance can provide it efficiently.

What life insurance solutions do business owners need most?

The most common are buy-sell funding, key person coverage and executive bonus plans. Family businesses also use life insurance for estate liquidity and inheritance equalization.

How can life insurance help with a family business succession?

It can provide cash to keep the business running, pay estate costs, or give children who are not in the business an equal inheritance so ownership can pass to the child who is.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-26

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.
