
Call 303-309-3471 Advisors: get contracted with SRS →Get a Quote
Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim Fuller is President of SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency) that has connected independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners for more than 50 years. Tim and the SRS team specialize in impaired-risk underwriting, advanced case design, and helping advisors place the cases other IMOs turn away.

Life InsuranceImpaired RiskLong-Term CareDisability IncomeAdvanced MarketsUnderwriting
Connect with Tim on LinkedIn →

How a Disability Affects Social Security and Retirement Timing

Active retired couple walking their dog on a coastal trail, representing retirement planning

Clients who think about disability usually focus on paying the bills. Fewer think about what it does to retirement, including how Social Security treats years spent disabled and why savings rarely recover.

Key takeaways

  • If approved for SSDI, benefits automatically convert to retirement benefits at full retirement age, generally at the same amount.
  • A Social Security disability “freeze” excludes disabled years from the benefit calculation, but approval can be difficult.
  • Lost contributions and forced withdrawals during disability are the bigger threat to retirement, and can be insured.

Even high earners often aren’t saving enough for retirement. Add a disability, and saving becomes nearly impossible.

What happens to Social Security

If a client qualifies for Social Security Disability Insurance (SSDI), their benefit is based on their earnings record, and a disability freeze keeps the disabled years from lowering the calculation. At full retirement age, SSDI converts to a retirement benefit, generally at the same amount. But SSDI uses a strict definition of disability, has a five-month waiting period, and many initial claims are denied, so clients shouldn’t count on it.

What happens to savings

Contributions stop, employer matches stop, and many people withdraw from retirement accounts to cover expenses, often with taxes and penalties. Years of lost compounding can push retirement back substantially.

Protecting both income and retirement

Individual disability insurance protects the paycheck. Disability retirement coverage pays up to a set percentage of income into a trust each month during disability, subject to carrier maximums, so saving continues. See protecting retirement contributions.

Sales approaches

  • Pair individual DI and retirement protection in the same conversation.
  • Approach clients at maximum individual DI issue limits.
  • Approach clients who max out their 401(k).
  • Offer retirement protection to business owners as an executive benefit.

Frequently asked questions

What happens to Social Security disability at retirement age?

SSDI benefits automatically convert to retirement benefits at full retirement age, generally at the same amount.

Does disability reduce my Social Security retirement benefit?

If approved for SSDI, a disability freeze generally keeps disabled years from lowering the benefit calculation.

Can I keep saving for retirement while disabled?

Only if you have income for it. Disability retirement coverage can pay contributions into a trust while you’re disabled.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-25

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Reviewing Client Tax Returns to Find Planning Opportunities

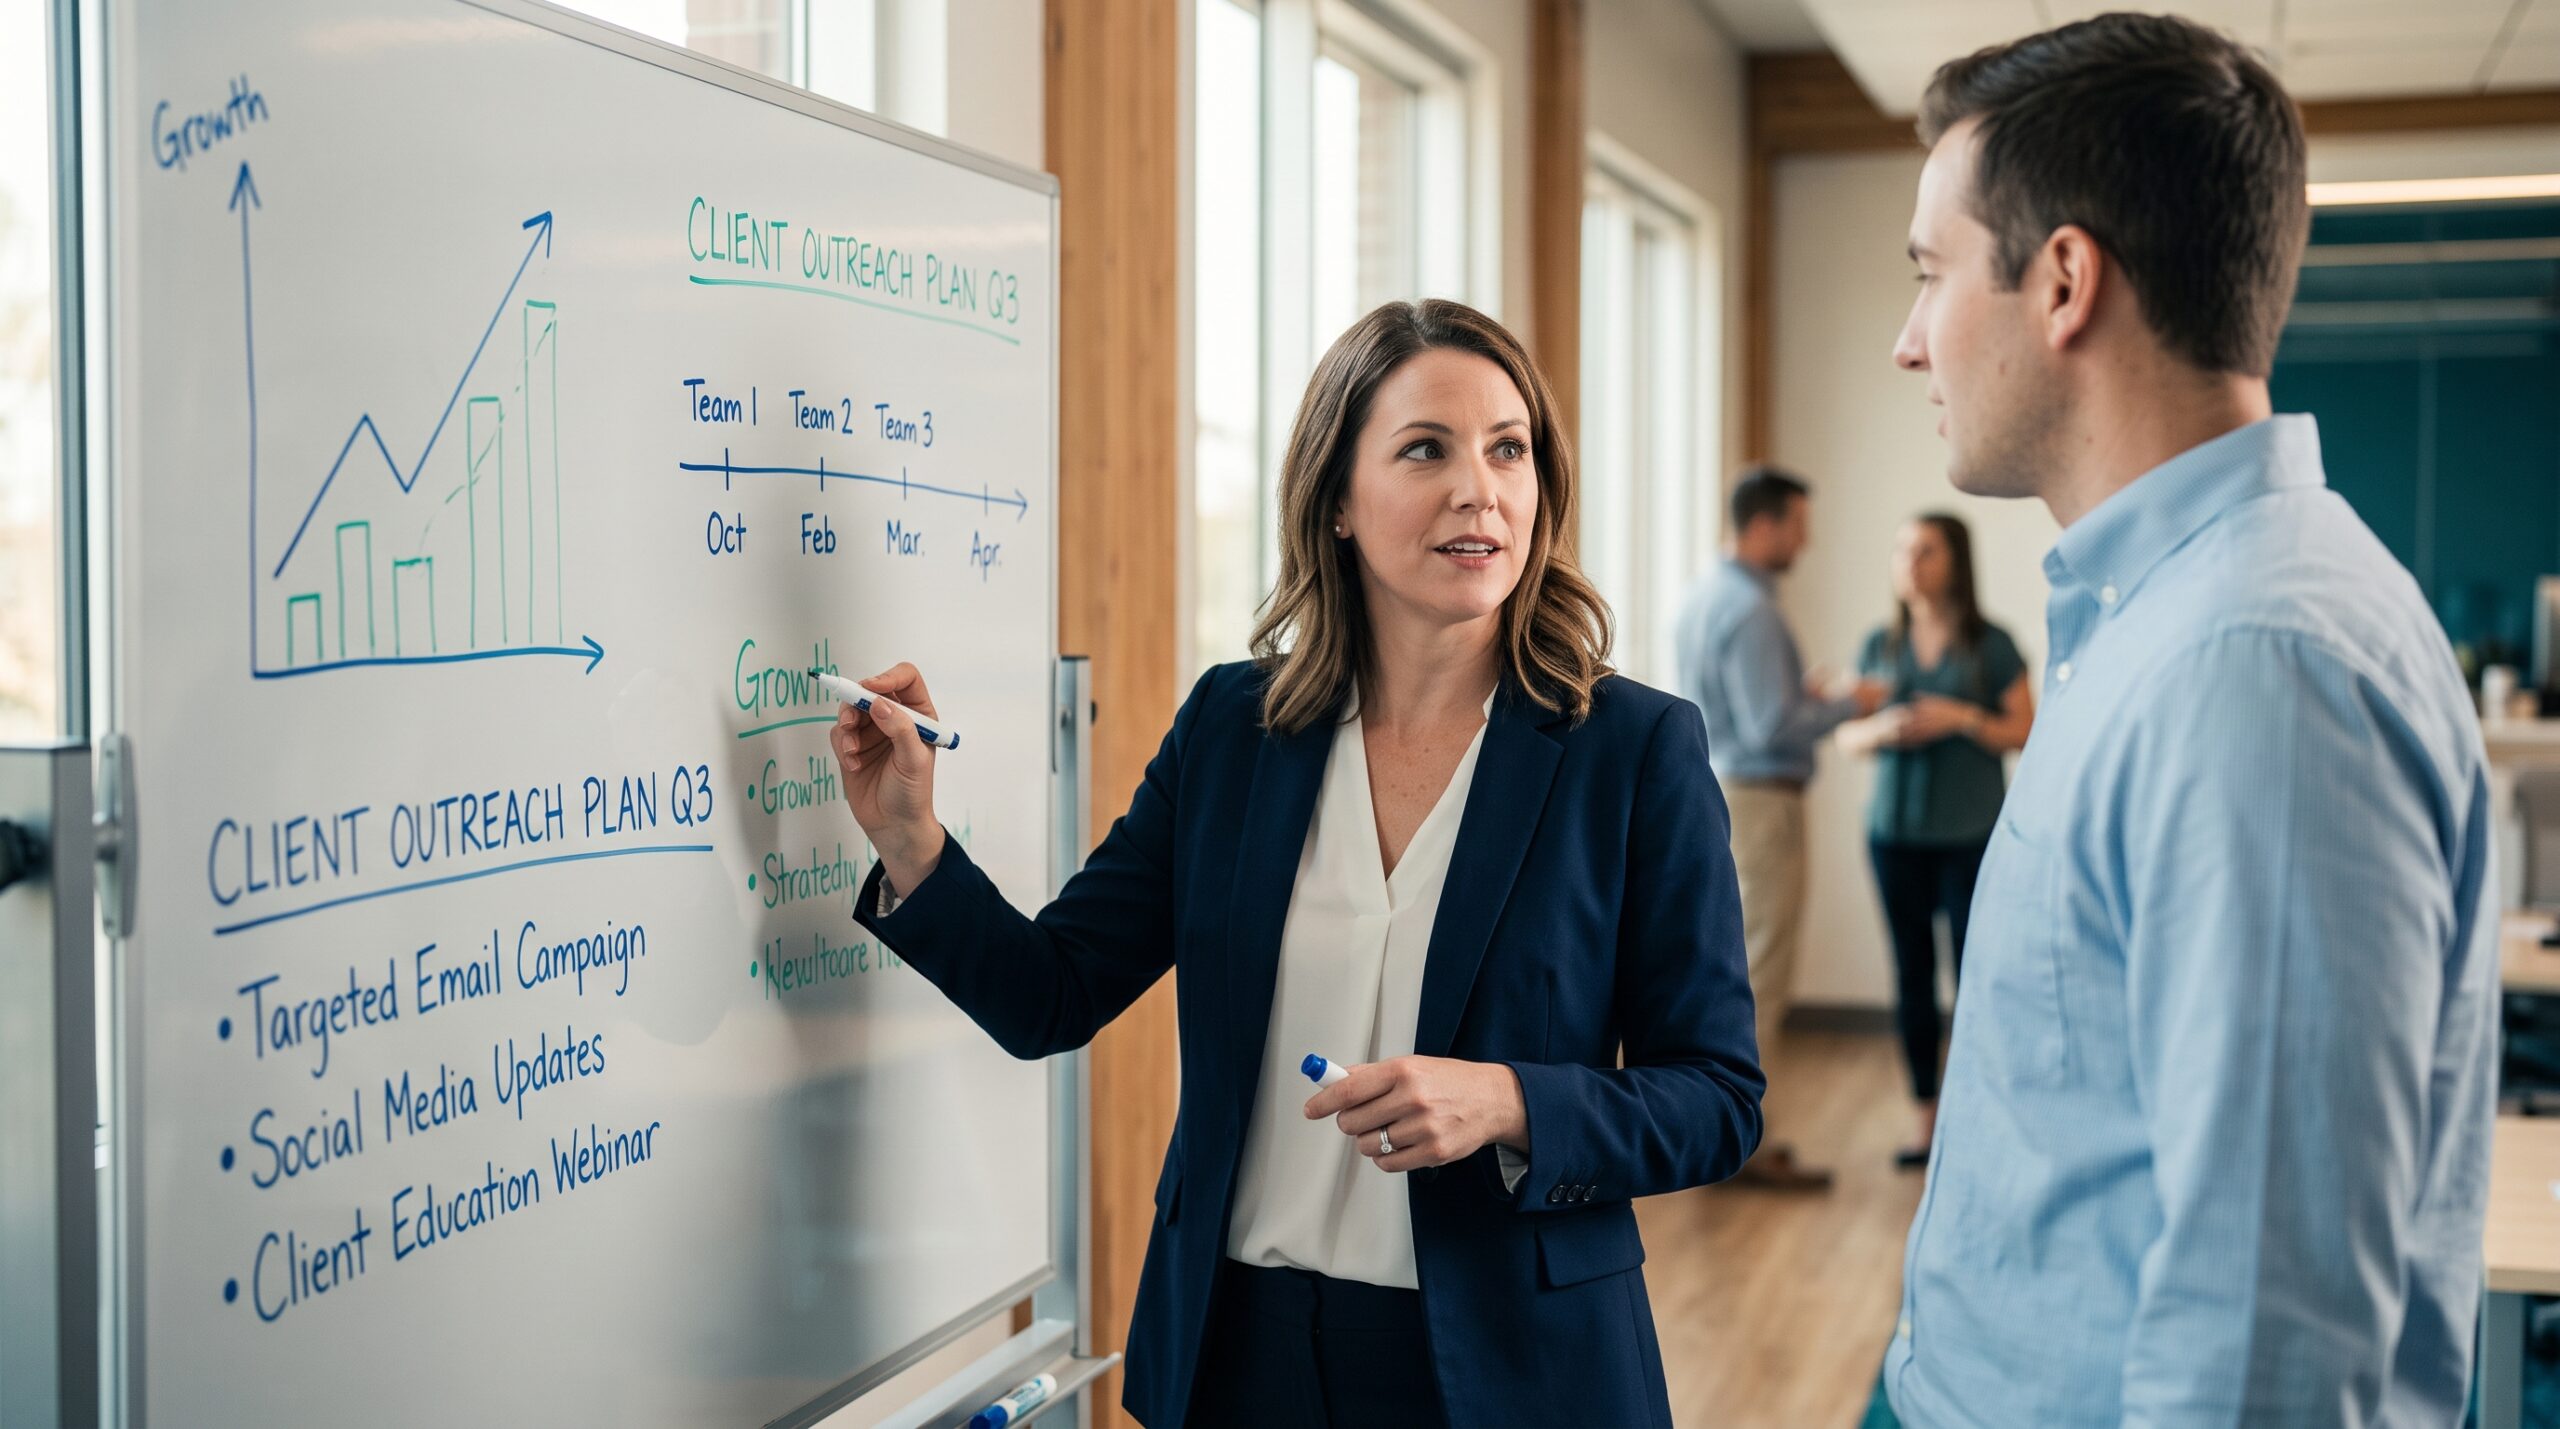
Advisor presenting a client outreach marketing plan on a whiteboard to a colleague

Right after filing season, the last thing most clients want to revisit is their tax return. That’s exactly why it’s a good time to do it. A return is a detailed map of a client’s income, assets and planning gaps, and reviewing it early gives you the rest of the year to act.

Key takeaways

  • A client’s tax return shows income sources, business ownership, retirement distributions and taxable savings, all of which point to planning needs.
  • Reviewing returns in spring leaves time to act, rather than scrambling after New Year’s when few options remain.
  • Carrier tax-return review materials and CPA relationships can make the process more focused and generate referrals.

Left to themselves, clients will wait until after New Year’s to ask how to cut this year’s taxes, when there’s little left you can do.

Why spring is the right time

Most clients call about taxes in December or January, when the only remaining moves may be a qualified plan contribution or two. Reviewing last year’s return soon after filing flips that timing. You have the full year to recommend changes and implement them.

What to look for on a return

  • Business income (Schedule C, Schedule E or K-1s): signals a business owner who may need key person coverage, buy-sell funding or an executive benefit plan.
  • Taxable interest and dividends: money sitting in taxable accounts that may be better positioned for growth, liquidity or legacy goals.
  • IRA and pension distributions: clients taking required minimum distributions they don’t need may want to redirect them. See using RMDs in life insurance sales.
  • Charitable deductions: a sign of charitable intent that could support gifting or legacy strategies.
  • Dependents: a reminder to check that income replacement and education funding are covered.

Tools and partners that help

Several carriers offer materials that walk through a client’s return line by line, with commentary on planning opportunities and suggested next steps. Ask us what’s currently available. These materials also work well with CPAs, who can use them to review the returns of clients they might refer to you for planning help.

Stay in your lane

Your role is to identify opportunities, not to prepare returns or give tax advice. Frame findings as questions for the client and their tax professional. That approach builds trust with both the client and the CPA and tends to produce more referrals over time.

Frequently asked questions

Why should financial advisors review client tax returns?

Returns reveal income sources, business ownership, retirement distributions, taxable savings and charitable giving. Each can point to planning needs such as life insurance, business succession or retirement income strategies.

When is the best time to review a client’s tax return?

Soon after it’s filed in the spring. That leaves the rest of the year to implement changes, rather than waiting until the end of the year when few options remain.

Can I give tax advice from a client’s return?

No. Advisors should identify opportunities and raise questions, then coordinate with the client’s CPA or tax professional for tax advice and preparation.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-26

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Term/UL Hybrid Products: An Option for Clients With Underperforming Policies

Happy family of four laughing together on the couch, representing life insurance protection

A policy review is one of the best ways to open a conversation with a new or existing client. Many older universal life policies are underperforming and may need higher premiums to stay in force. Term/UL hybrid products can give those clients a more affordable path forward.

Key takeaways

  • Many older universal life policies are underperforming, and some are in danger of lapsing without higher premium payments.
  • Term/UL hybrids combine the flexible premiums of universal life with the affordability of term, and many accept a single premium from a 1035 exchange.
  • Moving cash value before it’s exhausted can help a client lower ongoing premiums, buy a paid-up policy or secure more death benefit.

Before cash values are exhausted paying for an already unaffordable policy, show clients how a 1035 exchange could put that money to better use.

Why policy reviews open doors

When you review a client’s existing coverage, you’ll often find a policy performing well below its original illustration. Many universal life policies were sold assuming higher interest crediting rates, and some now require larger premiums to avoid lapse. Clients on fixed incomes may struggle to keep paying even the original premium. For timing and warning signs, see older UL policies at risk of lapse.

How term/UL hybrid products work

Term/UL hybrids are universal life policies designed to compete on price with term. They typically combine:

  • Flexible premiums, including a single payment funded by a 1035 exchange, which a traditional term plan can’t accept.
  • Guarantee periods that commonly run 10, 15, 20 or 30 years.
  • A longer secondary guarantee that, on some products, can extend coverage as far as age 121 if the client pays a higher premium, without new medical or financial underwriting.

Product designs vary by carrier, so confirm current features and availability before you present one.

Using a 1035 exchange

A 1035 exchange lets a client move cash value from an existing life policy into a new one without triggering income tax on the gain, provided the exchange is done correctly. With a hybrid, that cash value can be used to:

  • Lower the client’s ongoing premium
  • Purchase a paid-up policy
  • Secure a greater death benefit for the same outlay

Learn more about when a 1035 exchange makes sense.

Before you recommend a change

  • Request an in-force illustration of the current policy at current and guaranteed assumptions.
  • Compare surrender charges, any outstanding loans and the client’s current insurability.
  • Keep the old policy in force until the new one is approved and issued.
  • Document why the change is in the client’s best interest and follow state replacement rules.

Our life sales desk can help you compare options side by side.

Frequently asked questions

What is a term/UL hybrid life insurance policy?

It’s a universal life policy priced to compete with term. It offers guarantee periods like term, such as 10 to 30 years, plus flexible premiums and, on some products, the option to extend coverage later without new underwriting.

Can I 1035 exchange an old UL policy into a term/UL hybrid?

Often, yes. Many hybrids accept a single premium from a 1035 exchange, which traditional term can’t. The exchange must be done properly to avoid tax on any gain, and the new policy should be issued before the old one is surrendered.

How do I know if a client’s UL policy is at risk of lapsing?

Order an in-force illustration at current and guaranteed assumptions. If it shows the policy lapsing before the client’s life expectancy at the current premium, it’s time to discuss options.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-26

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Cholesterol Medications and Ratio-Based Underwriting: Best Rates With High Total Cholesterol

Doctor and patient reviewing a health chart on a tablet, representing health impairment underwriting

Cholesterol itself isn’t bad; the body needs it. What matters to many underwriters is the balance between good and bad cholesterol. Some carriers now look only at the ratio, and that can mean best-class rates for clients with high total cholesterol, even those on medication.

Key takeaways

  • HDL is “good” cholesterol and LDL is “bad”; the total cholesterol-to-HDL ratio is a key risk indicator.
  • One carrier ignores total cholesterol (up to 300) and uses only the ratio.
  • Clients taking cholesterol medication can still qualify for Preferred classes with favorable ratios.

Total cholesterol of 298 and no medication — but a 5.0 ratio earned Preferred Best on $2 million.

Understanding the ratio

The cholesterol/HDL ratio is total cholesterol divided by HDL. Higher HDL drives the ratio down, which indicates lower heart disease risk. Many underwriters find the ratio more predictive than total cholesterol alone.

Ratio-only underwriting

One of our A+ carriers no longer considers total cholesterol, up to a maximum of 300, and reviews only the ratio. Other top carriers use similar approaches. Cholesterol medications such as statins, when they produce good results, generally aren’t a barrier. See high cholesterol cases for more.

Examples

  • Male, 45, non-smoker, $2 million term: cholesterol 298, ratio 5.0, no medication: Preferred Best.
  • Female, 60, non-smoker, $1 million UL: cholesterol 275, ratio 6.0, on cholesterol medication: Preferred.
  • Male, 52, non-smoker, $500,000 term: cholesterol 260, ratio 7.0, on medication: Non-Smoker Plus.

Frequently asked questions

Does taking a statin affect life insurance rates?

Not necessarily. Many carriers focus on the results, and well-controlled cholesterol on medication can still qualify for Preferred.

What cholesterol ratio do life insurers want?

It varies by carrier and class, but lower is better. Some carriers offer best rates with ratios around 5.0.

Do life insurers look at total cholesterol or HDL?

Many look at both, but some focus only on the cholesterol/HDL ratio, up to a total cholesterol cap.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-25

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Generating Long-Term Care Leads From Your Existing Client Reviews

Adult daughter and her aging mother sharing a warm moment while discussing long-term care planning

Seminars and direct mail can generate long-term care leads, but they’re costly and slow. Your best leads may already be in your database: clients who said “not now” because of price.

Key takeaways

  • Past prospects who stalled on price are warm leads when you can show a more affordable design.
  • A short follow-up meeting to revisit needs and budget often restarts the conversation.
  • Tailored, needs-based materials shorten the sales cycle.

The client who said “too expensive” two years ago may say yes to a plan designed around their budget today.

Step 1: Find price-sensitive prospects

Search your client and prospect records for people who were interested but didn’t buy because of cost. New designs, including hybrids, riders, shorter benefit periods, and couples discounts, may now fit. See couples discounts and asymmetrical designs.

Step 2: Schedule a short meeting

Reach out to each and schedule a brief review of what they need and what they can spend. Use the annual review questions in LTC fact-finding at the annual review.

Step 3: Use tailored materials

Needs-based, personalized proposals and marketing support shorten the sales cycle. Contact our LTC team for materials and side-by-side designs.

Frequently asked questions

Where can I find long-term care insurance leads?

Start with existing clients and past prospects, especially those who hesitated over price, then add referrals and community events.

How do I re-engage a prospect who said LTC was too expensive?

Offer a short meeting to review needs and budget, and present lower-cost designs such as shorter benefit periods or hybrid options.

Are seminars good for LTC lead generation?

They can work but are costly and slow. Mining your existing book is often faster and cheaper.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-25

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

What Happens When a Client Dies Without a Will: Why Documenting Intentions Matters

Advisor and client reviewing an advanced markets estate planning strategy in a private office

All 50 states effectively say the same thing about a client’s planning goals: if they aren’t written down, they didn’t happen. When a client dies or becomes incapacitated without the right documents, state law fills in the blanks. Helping clients understand those defaults is often what finally gets them to act.

Key takeaways

  • Estate planning isn’t just for the wealthy. Everyone has people and property that would be affected by death or incapacity.
  • Without written documents, state intestacy and guardianship laws decide who inherits, who manages money and who cares for minor children.
  • Advisors can encourage clients to complete their core documents with an attorney and make sure beneficiary designations support the plan.

If a client’s wishes aren’t written down, then as far as the state is concerned, they didn’t happen.

“If it isn’t written down, it didn’t happen”

Thriller fans may recognize that line from Tom Clancy’s novels, where Jack Ryan’s wife, a busy physician, writes everything down to keep track of everyone’s commitments. Whole productivity programs have been built around the idea. State legislatures got there first. When it comes to a client’s estate, what isn’t documented doesn’t count.

Who needs estate planning?

Everyone, not just the wealthy. Every client has concerns about what happens to themselves, their survivors and their belongings after death or a serious illness. A young parent needs a guardian named for their children. A retiree needs someone authorized to manage accounts if dementia sets in. A business owner needs a plan for their share of the company.

What the state decides when there’s no plan

  • Who inherits: State intestacy rules distribute probate assets by a fixed formula, which may not match the client’s wishes, especially in blended families.
  • Who manages the estate: A court appoints an administrator.
  • Who raises minor children: A judge chooses the guardian.
  • Who handles money and medical care during incapacity: Without a power of attorney and health care directive, family may need a court-supervised guardianship or conservatorship.

For the three documents that prevent these outcomes, see the core estate planning documents every client needs.

How advisors can help

Ask every client whether they have a current will, power of attorney and health care directive, and refer them to an attorney to complete or update them. Then review beneficiary designations on life insurance, annuities and retirement accounts, since those generally pass outside the will. Our article on the beneficiary review walks through that step. Contact us if you’d like help discussing these documents with clients.

Frequently asked questions

What happens if someone dies without a will?

State intestacy laws decide who inherits the person’s probate assets, a court appoints someone to administer the estate, and a judge chooses a guardian for any minor children.

Does life insurance go through probate if there’s no will?

Generally no. Life insurance paid to a named, living beneficiary passes outside the will and probate. If the beneficiary is the estate, or no beneficiary survives, the proceeds may become part of the probate estate.

Do young or middle-income clients need estate planning?

Yes. Anyone with children, property, retirement accounts or people who depend on them benefits from a will, power of attorney and health care directive.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-26

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.
Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

3 Living-Benefit Uses of Indexed Universal Life That Help Place More Cases

Advisor supporting a couple as they review living needs benefits paperwork together

Life insurance is more than a death benefit. As clients approach retirement, their concerns shift from income replacement toward outliving their savings and paying for health care. A properly designed indexed universal life policy can speak to those concerns, and positioning its living benefits can help you win more cases.

Key takeaways

  • Three common pre-retirement uses of IUL are college expenses, supplemental retirement income and long-term care or chronic illness costs.
  • IUL offers access, growth and protection: liquidity through withdrawals and loans, index-linked crediting with a floor, and a flexible death benefit.
  • Design matters. Funding level, loan strategy and riders determine how well a policy delivers these benefits.

There are numerous living benefits attached to life insurance, and they are available long before the death benefit is ever paid.

Why living benefits win cases

Many clients push back on life insurance because they see it only as money for someone else after they die. Showing how a policy can help them while they’re alive changes the conversation. For a broader overview, see the living benefits of permanent life insurance.

Three pre-retirement uses of IUL

  1. College expenses. Accumulated cash value can be accessed through withdrawals or policy loans to help pay for a child’s or grandchild’s education.
  2. Supplemental retirement income. A properly funded policy can provide a stream of withdrawals and loans that may be income-tax-free, alongside Social Security and qualified plans.
  3. Long-term care and chronic illness costs. Many IUL policies offer a chronic illness or long-term care rider that lets the insured accelerate part of the death benefit if they qualify.

Access, growth and protection

  • Access: Cash value can be reached through withdrawals and policy loans, generally without income tax if the policy stays in force and isn’t a modified endowment contract.
  • Growth: Interest is credited based on the performance of an index such as the S&P 500, subject to caps or participation rates. A floor, often 0%, means index credits don’t go negative when the market falls, though policy charges still apply.
  • Protection: Flexible death benefit options, plus riders that can provide funds for chronic illness or ongoing care.

Positioning it responsibly

Illustrate at reasonable crediting rates, show how loans reduce the death benefit, and make sure the premium is one the client can sustain. Our life sales team can help you design the policy, choose riders and build a presentation that explains these features clearly.

Frequently asked questions

What are the living benefits of indexed universal life?

IUL cash value can be accessed during life for needs like college costs or supplemental retirement income, and many policies include riders that accelerate the death benefit for chronic illness or long-term care.

Can clients lose money in an IUL when the market drops?

Index credits typically have a floor, often 0%, so a market decline doesn’t produce a negative credit. However, policy charges continue, so cash value can still decrease in years with little or no credited interest.

Are IUL withdrawals and loans tax-free?

They can be income-tax-free when the policy is structured properly, stays in force and isn’t a modified endowment contract. Loans reduce the death benefit, and a lapse with a loan outstanding can create taxable income.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-26

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Case Placement: Declined for Heart Attack History, Placed at Standard

Underwriter reviewing medical and financial data with a client during risk assessment

A decline from one source isn’t the end of the road. This client had a heart attack and a stent, was declined elsewhere, and was placed at Standard Non-Tobacco after we took a second look.

Key takeaways

  • Cardiac declines are often worth re-shopping, especially with good follow-up testing.
  • Normal stress tests and controlled cholesterol after a heart attack are strong positives.
  • A 69-year-old with a prior heart attack and stent received Standard Non-Tobacco on $1 million of term.

Declined elsewhere for a heart attack and stent. Our result: Standard Non-Tobacco on $1 million, a placed case with $13,500 in annual premium.

The case

  • Male, age 69, non-smoker, seeking $1 million of term
  • Previously declined based on cardiac history
  • April 2015: heart attack with a successful stent for a severe right coronary artery blockage; mild blockages in two other arteries that needed no treatment
  • Echocardiograms in 2015, 2018, and 2019 showed a mildly enlarged left atrium
  • Stress testing showed normal heart function with no ischemia (reduced blood flow)
  • Current cholesterol normal

The outcome

We negotiated with one of our carriers and obtained Standard Non-Tobacco. The case was placed with an annual premium of $13,500.

What made it work

Underwriters look for stability after a cardiac event: normal stress tests, no ongoing symptoms, controlled risk factors, and consistent follow-up. This client had all of them. The original decline didn’t reflect how well he was doing. We’ve seen similar results with coronary artery disease at age 72.

Send us your declines

If you have a recently declined case, send it to our Underwriting Team for a fresh look. Include the most recent cardiac testing and cardiologist notes.

Frequently asked questions

Can you get life insurance after a heart attack?

Yes. Many clients qualify, especially with stable follow-up testing and controlled risk factors. Some can reach Standard or better.

Is a stent a problem for life insurance?

Not by itself. Underwriters focus on how the heart has done since, including stress tests, echocardiograms, and symptoms.

Should I re-shop a declined cardiac case?

Yes. Carriers differ widely on cardiac history, and a decline at one company can be an offer at another.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-25

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.

Honoring a Last Wish to Die at Home: Why a Long-Term Care Plan Matters

Adult daughter and her aging mother sharing a warm moment while discussing long-term care planning

“What’s your plan?” It’s the question we encourage advisors to ask every client about long-term care, because when there isn’t one, the consequences can be heartbreaking.

Key takeaways

  • Most people want to receive care, and spend their final days, at home.
  • Without private coverage, the rules of Medicare and Medicaid can make extended in-home care very hard to arrange.
  • A comprehensive long-term care plan preserves the choice of where and how care is received.

A long-term care plan isn’t just about money. It’s about being able to choose where you spend the end of your life.

A story that shows the stakes

A New York Times article, “Fighting to Honor a Father’s Last Wish: To Die at Home,” followed one family’s struggle to keep their father at home. It showed how the requirements of Medicare and Medicaid can make it nearly impossible to arrange enough in-home care, even when that’s what the patient and family want.

Why government programs fall short

Medicare covers only limited skilled care, not ongoing custodial help at home. Medicaid generally requires spending down assets and may limit home care hours and options. See what Medicare and Medicaid actually cover.

What a comprehensive plan provides

A comprehensive long-term care policy can cover home care, adult day care, hospice-related support, assisted living, and nursing home care. Most importantly, it gives the insured the dignity and independence to choose where they receive care. More on home care benefits.

Your role

Advisors have a real opportunity to protect clients’ dignity, not just their assets. Ask the question, and help them build a plan that fits their budget.

Frequently asked questions

Does long-term care insurance pay for care at home at the end of life?

Many comprehensive policies cover home care, and some include hospice-related support, allowing people to stay home.

Why is it hard to get extended home care through Medicare or Medicaid?

Medicare doesn’t cover ongoing custodial care, and Medicaid has asset limits and may restrict home care hours and options.

What question should advisors ask about long-term care?

Simply, “What’s your plan?” Most clients haven’t made one.

50+ Years in Business60+ Top-Rated Carriers★★★★★ Rated by Advisors

Reviewed by Tim Fuller on 2026-09-25

Tim Fuller, President of SRS Inc.

Tim Fuller

President, SRS Inc.

Tim leads SRS Inc., a full-service IMO (Independent Marketing Organization) and BGA (Brokerage General Agency), connecting independent financial professionals with life, annuity, disability income, and long-term care solutions from 60+ carrier partners.

Connect on LinkedIn →

We’re Here to Help

Have a question about what you just read, or a case you’re working on? Tell us a bit about what you need, and a member of the SRS team will follow up with you personally — no obligation, no hassle.

Name(Required)
Email(Required)
Please let us know what's on your mind. Have a question for us? Ask away.
This field is for validation purposes and should be left unchanged.
